
American Express (AXP)
Issues cards and operates an integrated merchant-acquiring and payments network.
Something off on this page? Send us feedback.
American Express runs both sides of a card purchase: it lends to cardholders and connects merchants to the payment. U.S. consumers remain its largest business, international cards are growing fastest, and dining tools plus expense software are widening what the card relationship can do. The model hangs on spending, repayment, rewards people value, and merchants willing to accept the card.
Item facts: FY2025 · year ended Dec 31, 2025, from filings, earnings calls and company pages.
Judgment weights, not filed revenue
The band summarizes business focus and direction. ~ marks estimates.
8 in detail · 12 more below
U.S. Consumer Services
The largest business issues cards to U.S. consumers and carries their unpaid balances. Revenue grew 11% in the quarter ended June 2026; watch whether spending and fees keep rising without missed repayments undoing the gain.
Competes with Chase Sapphire Reserve (JPMorgan Chase) · Venture X Rewards (Capital One)
In plain English
Start with the biggest piece: American Express gives U.S. consumers cards, pays merchants when those cards are used, and collects from cardholders later. It is part payment pass, part short-term lender.
Money arrives three ways. Merchants pay when a cardholder shops, many cardholders pay an annual fee for benefits, and borrowers pay interest when they carry a balance. People keep the card when its rewards and travel perks feel worth the fee; American Express makes money when those customers spend heavily and repay reliably.
International Card Services
Cards for consumers and businesses outside the U.S. are the fastest-growing major piece. Revenue rose 12% in the quarter ended June 2026; acceptance, local rules, currencies, and how reliably local customers repay decide how far that lead travels.
Competes with Visa Infinite programs (Visa) · World Elite Mastercard programs (Mastercard)
In plain English
Outside the United States, American Express repeats its card business country by country. It issues cards to people and companies, lends against some balances, and in certain markets lets local banks put cards onto its payment network.
Picture the same shop rebuilt with different doors for each country: local rules, currencies, bank partners, and merchant coverage all have to fit. Cardholders pay fees and interest, while merchants pay when those cards are used. The business grows when more places accept the card and travelers and local customers choose it often enough to justify the benefits.
Delta SkyMiles American Express Cards
Delta is the one plainly large named partner. Its airline-linked cards are unusually important to both American Express spending and lending; the agreement runs through 2029, making renewal terms and travel demand central watch points.
Competes with United Club Card (United Airlines / JPMorgan Chase) · Citi / AAdvantage Executive (American Airlines / Citigroup)
In plain English
One airline matters more than any other named partner. These cards combine American Express payment and lending with Delta miles and travel benefits, giving frequent flyers a reason to put more purchases on one card.
The arrangement works like a shop shared by two owners. American Express earns merchant charges, annual card fees, and interest from carried balances; Delta supplies the miles and benefits, and American Express pays Delta for them. The unusually large spending and loan exposure makes this relationship powerful, but it also means changes in travel demand or the next agreement could be felt across the card business.
Membership Rewards
Points tie card spending to travel, shopping, and bill credits. American Express expects 96% of earned points to be used, so the program must keep customers loyal without letting the cost of each reward outrun that value.
Competes with Chase Ultimate Rewards (JPMorgan Chase) · Capital One Miles (Capital One)
In plain English
Points are a promise. Spend on an eligible card now, then trade the points later for travel, shopping, money off a bill, or a transfer to a partner program.
It resembles a store stamp card, except the prizes come from a large web of airlines, hotels, retailers, and merchants. Those choices make the card harder to abandon and encourage more spending, which supports merchant charges and annual fees. American Express pays for the eventual reward, though, so popular redemptions help loyalty while more expensive rewards can quickly raise the bill.
American Express Dining Platform
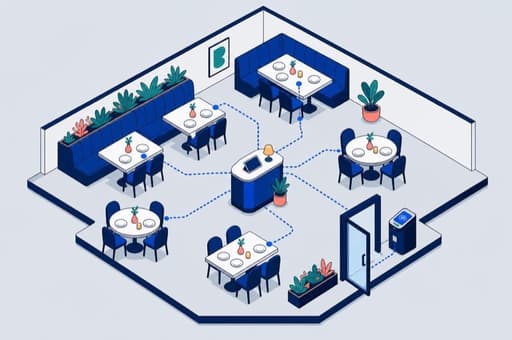
Resy, Tock, Rooam, and the pending TheFork purchase join restaurant discovery, reservations, venue software, and mobile payment. The combined footprint would reach roughly 75,000 venues; watch whether the deal closes and turns dining access into card use.
Competes with OpenTable (Booking Holdings) · SevenRooms (SevenRooms)
In plain English
A dinner reservation may look far removed from a card company, but it gives American Express a place to shape where cardholders spend. Resy helps diners find tables, Tock gives venues booking tools, and Rooam adds phone-based payment; TheFork would extend the idea across Europe.
Restaurants supply tables and may pay for software, while diners create booking and restaurant spending. For now, the clearest payoff for American Express is stronger card use: special access makes its cards more useful, and a path from choosing a restaurant to paying the bill can steer more activity through those cards.
Commercial Services
Business and corporate cards sit beside supplier payments, short-term funding, and expense tools. Revenue grew 7% in the quarter ended June 2026, the slowest major segment pace; watch whether it can keep growing as software-led rivals court the same finance teams.
Competes with Ramp Card and Expense Management (Ramp) · Brex Corporate Card and Spend Management (Brex)
In plain English
The company card has become an office tool. Employees use it for travel and purchases; finance teams use connected controls and records to see where money went; businesses can also pay suppliers or cover short gaps in cash.
American Express earns merchant charges when workers spend, card fees for access and benefits, and interest on borrowed balances. Connections to accounting and expense systems make the card easier to build into daily work. That convenience helps keep companies attached, but newer rivals such as Ramp and Brex sell the software experience first and the card alongside it.
Center Expense Management Platform
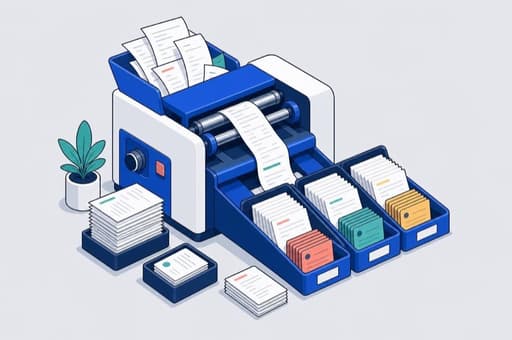
Center wraps company cards in spending rules, receipt capture, accounting connections, and employee steps. Added in April 2025, it helps American Express compete for the whole finance routine; watch whether it draws more spending onto the wider business-card service.
Competes with Ramp Expense Management (Ramp) · Brex Spend Management (Brex)
In plain English
Center is the software around the purchase. A company can set rules before an employee spends, collect the receipt afterward, and send the record toward its accounting system without chasing paper by hand.
Think of it as a mailroom that sorts every expense before it reaches the bookkeeper. Finance teams pay with American Express cards and get less administrative work in return; the company benefits when that convenience draws more business spending onto its cards. American Express is folding Center into the wider business-card offer, so progress has to show up through stronger use of that service.
Global Merchant and Network Services
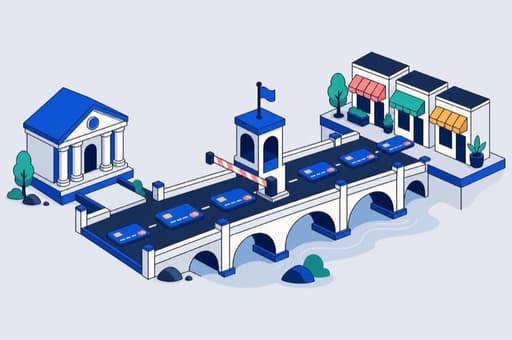
This business signs merchants, carries payment messages, and lets outside banks offer cards on the network. It handled $1.897 trillion in FY2025 activity; merchant coverage, reliability, fraud control, and pricing determine whether that flow keeps widening.
Competes with Visa global card network (Visa) · Mastercard global card network (Mastercard)
In plain English
Every American Express purchase needs a path from checkout to approval. This business builds that path, signs stores to accept the card, moves the payment instructions, and lets some outside banks offer cards that use the same payment route.
It works like a toll bridge between shoppers, banks, and merchants. More accepted locations make the card more useful; more useful cards bring merchants more customers. American Express earns from that movement and from payments made with cards offered by outside banks. The loop only holds if the bridge stays reliable, fraud stays controlled, and merchants believe the customers it brings are worth the price.


 U.S. Consumer ServicesThe largest business issues cards to U.S. consumers and carries their unpaid balances. Revenue grew 11% in the quarter ended June 2026; watch whether spending and fees keep rising without missed repayments undoing the gain.
The largest business issues cards to U.S. consumers and carries their unpaid balances. Revenue grew 11% in the quarter ended June 2026; watch whether spending and fees keep rising without missed repayments undoing the gain.
In plain English
Start with the biggest piece: American Express gives U.S. consumers cards, pays merchants when those cards are used, and collects from cardholders later. It is part payment pass, part short-term lender.
Money arrives three ways. Merchants pay when a cardholder shops, many cardholders pay an annual fee for benefits, and borrowers pay interest when they carry a balance. People keep the card when its rewards and travel perks feel worth the fee; American Express makes money when those customers spend heavily and repay reliably.
Competes with Chase Sapphire Reserve (JPMorgan Chase) · Venture X Rewards (Capital One)
 International Card ServicesCards for consumers and businesses outside the U.S. are the fastest-growing major piece. Revenue rose 12% in the quarter ended June 2026; acceptance, local rules, currencies, and how reliably local customers repay decide how far that lead travels.
Cards for consumers and businesses outside the U.S. are the fastest-growing major piece. Revenue rose 12% in the quarter ended June 2026; acceptance, local rules, currencies, and how reliably local customers repay decide how far that lead travels.
In plain English
Outside the United States, American Express repeats its card business country by country. It issues cards to people and companies, lends against some balances, and in certain markets lets local banks put cards onto its payment network.
Picture the same shop rebuilt with different doors for each country: local rules, currencies, bank partners, and merchant coverage all have to fit. Cardholders pay fees and interest, while merchants pay when those cards are used. The business grows when more places accept the card and travelers and local customers choose it often enough to justify the benefits.
Competes with Visa Infinite programs (Visa) · World Elite Mastercard programs (Mastercard)
 Delta SkyMiles American Express CardsDelta is the one plainly large named partner. Its airline-linked cards are unusually important to both American Express spending and lending; the agreement runs through 2029, making renewal terms and travel demand central watch points.
Delta is the one plainly large named partner. Its airline-linked cards are unusually important to both American Express spending and lending; the agreement runs through 2029, making renewal terms and travel demand central watch points.
In plain English
One airline matters more than any other named partner. These cards combine American Express payment and lending with Delta miles and travel benefits, giving frequent flyers a reason to put more purchases on one card.
The arrangement works like a shop shared by two owners. American Express earns merchant charges, annual card fees, and interest from carried balances; Delta supplies the miles and benefits, and American Express pays Delta for them. The unusually large spending and loan exposure makes this relationship powerful, but it also means changes in travel demand or the next agreement could be felt across the card business.
Competes with United Club Card (United Airlines / JPMorgan Chase) · Citi / AAdvantage Executive (American Airlines / Citigroup)
 Membership RewardsPoints tie card spending to travel, shopping, and bill credits. American Express expects 96% of earned points to be used, so the program must keep customers loyal without letting the cost of each reward outrun that value.
Points tie card spending to travel, shopping, and bill credits. American Express expects 96% of earned points to be used, so the program must keep customers loyal without letting the cost of each reward outrun that value.
In plain English
Points are a promise. Spend on an eligible card now, then trade the points later for travel, shopping, money off a bill, or a transfer to a partner program.
It resembles a store stamp card, except the prizes come from a large web of airlines, hotels, retailers, and merchants. Those choices make the card harder to abandon and encourage more spending, which supports merchant charges and annual fees. American Express pays for the eventual reward, though, so popular redemptions help loyalty while more expensive rewards can quickly raise the bill.
Competes with Chase Ultimate Rewards (JPMorgan Chase) · Capital One Miles (Capital One)
 American Express Dining PlatformResy, Tock, Rooam, and the pending TheFork purchase join restaurant discovery, reservations, venue software, and mobile payment. The combined footprint would reach roughly 75,000 venues; watch whether the deal closes and turns dining access into card use.
Resy, Tock, Rooam, and the pending TheFork purchase join restaurant discovery, reservations, venue software, and mobile payment. The combined footprint would reach roughly 75,000 venues; watch whether the deal closes and turns dining access into card use.
In plain English
A dinner reservation may look far removed from a card company, but it gives American Express a place to shape where cardholders spend. Resy helps diners find tables, Tock gives venues booking tools, and Rooam adds phone-based payment; TheFork would extend the idea across Europe.
Restaurants supply tables and may pay for software, while diners create booking and restaurant spending. For now, the clearest payoff for American Express is stronger card use: special access makes its cards more useful, and a path from choosing a restaurant to paying the bill can steer more activity through those cards.
Competes with OpenTable (Booking Holdings) · SevenRooms (SevenRooms)
 Commercial ServicesBusiness and corporate cards sit beside supplier payments, short-term funding, and expense tools. Revenue grew 7% in the quarter ended June 2026, the slowest major segment pace; watch whether it can keep growing as software-led rivals court the same finance teams.
Business and corporate cards sit beside supplier payments, short-term funding, and expense tools. Revenue grew 7% in the quarter ended June 2026, the slowest major segment pace; watch whether it can keep growing as software-led rivals court the same finance teams.
In plain English
The company card has become an office tool. Employees use it for travel and purchases; finance teams use connected controls and records to see where money went; businesses can also pay suppliers or cover short gaps in cash.
American Express earns merchant charges when workers spend, card fees for access and benefits, and interest on borrowed balances. Connections to accounting and expense systems make the card easier to build into daily work. That convenience helps keep companies attached, but newer rivals such as Ramp and Brex sell the software experience first and the card alongside it.
Competes with Ramp Card and Expense Management (Ramp) · Brex Corporate Card and Spend Management (Brex)
 Center Expense Management PlatformCenter wraps company cards in spending rules, receipt capture, accounting connections, and employee steps. Added in April 2025, it helps American Express compete for the whole finance routine; watch whether it draws more spending onto the wider business-card service.
Center wraps company cards in spending rules, receipt capture, accounting connections, and employee steps. Added in April 2025, it helps American Express compete for the whole finance routine; watch whether it draws more spending onto the wider business-card service.
In plain English
Center is the software around the purchase. A company can set rules before an employee spends, collect the receipt afterward, and send the record toward its accounting system without chasing paper by hand.
Think of it as a mailroom that sorts every expense before it reaches the bookkeeper. Finance teams pay with American Express cards and get less administrative work in return; the company benefits when that convenience draws more business spending onto its cards. American Express is folding Center into the wider business-card offer, so progress has to show up through stronger use of that service.
Competes with Ramp Expense Management (Ramp) · Brex Spend Management (Brex)
 Global Merchant and Network ServicesThis business signs merchants, carries payment messages, and lets outside banks offer cards on the network. It handled $1.897 trillion in FY2025 activity; merchant coverage, reliability, fraud control, and pricing determine whether that flow keeps widening.
This business signs merchants, carries payment messages, and lets outside banks offer cards on the network. It handled $1.897 trillion in FY2025 activity; merchant coverage, reliability, fraud control, and pricing determine whether that flow keeps widening.
In plain English
Every American Express purchase needs a path from checkout to approval. This business builds that path, signs stores to accept the card, moves the payment instructions, and lets some outside banks offer cards that use the same payment route.
It works like a toll bridge between shoppers, banks, and merchants. More accepted locations make the card more useful; more useful cards bring merchants more customers. American Express earns from that movement and from payments made with cards offered by outside banks. The loop only holds if the bridge stays reliable, fraud stays controlled, and merchants believe the customers it brings are worth the price.
Competes with Visa global card network (Visa) · Mastercard global card network (Mastercard)
Named in filings, launches and programs
- U.S. Consumer Platinum CardProductPremium consumer card refreshed in September 2025 with an $895 annual fee.
- U.S. Consumer Gold CardProductFee-bearing rewards card built around dining and everyday spending.
- U.S. Business Platinum CardProductPremium small-business card refreshed alongside the consumer Platinum portfolio in 2025.
- American Express TravelServiceBooks and services flights and hotels while delivering cardholder travel benefits through American Express channels.
- The Global Lounge CollectionEcosystemOwned and partner airport lounges turn physical travel access into a reason to keep a premium card.
- OptBlueEcosystemOutside payment processors help smaller merchants accept American Express, extending the network without every relationship being signed directly.
- High Yield Savings AccountProductConsumer savings deposits supply part of the money used to fund the company's card lending.
- Pay Over TimeServiceLets eligible cardholders carry purchases forward and pay interest instead of settling the full bill at once.
- Shop SmallCustomer programMerchant promotion and cardholder offers encourage spending at small businesses.
- American Express Agentic Commerce ExperiencesPlatform · AnnouncedPlanned tools would let AI assistants connect product discovery, offers, booking, and payment through American Express.
- SwisscardBrandSwiss card issuer brought fully inside International Card Services after American Express bought the remaining interest in January 2026.
- Amex VenturesEcosystemStrategic investment arm that connects financial-technology and shopping capabilities to the wider American Express platform.
U.S. Consumer Platinum CardProduct
Premium consumer card refreshed in September 2025 with an $895 annual fee.
U.S. Consumer Gold CardProduct
Fee-bearing rewards card built around dining and everyday spending.
U.S. Business Platinum CardProduct
Premium small-business card refreshed alongside the consumer Platinum portfolio in 2025.
American Express TravelService
Books and services flights and hotels while delivering cardholder travel benefits through American Express channels.
The Global Lounge CollectionEcosystem
Owned and partner airport lounges turn physical travel access into a reason to keep a premium card.
OptBlueEcosystem
Outside payment processors help smaller merchants accept American Express, extending the network without every relationship being signed directly.
High Yield Savings AccountProduct
Consumer savings deposits supply part of the money used to fund the company's card lending.
Pay Over TimeService
Lets eligible cardholders carry purchases forward and pay interest instead of settling the full bill at once.
Shop SmallCustomer program
Merchant promotion and cardholder offers encourage spending at small businesses.
American Express Agentic Commerce ExperiencesPlatform · Announced
Planned tools would let AI assistants connect product discovery, offers, booking, and payment through American Express.
SwisscardBrand
Swiss card issuer brought fully inside International Card Services after American Express bought the remaining interest in January 2026.
Amex VenturesEcosystem
Strategic investment arm that connects financial-technology and shopping capabilities to the wider American Express platform.