
Brown & Brown (BRO)
Places retail insurance and distributes specialty coverage through programs and wholesale brokerage.
Something off on this page? Send us feedback.
Brown & Brown sells other people's insurance and keeps a cut of the premium. Its offices arrange cover for small and mid-sized businesses, for the health plans those businesses give their staff, and for local public bodies; the insurer carries the risk. Growth has come more from buying rival brokers than from winning new business, and the biggest purchase yet reshaped the company. Whether it can grow on its own is the live question.
Item facts: H1 FY2026 · six months ended June 30, 2026, from filings, earnings calls and company pages.
Judgment weights, not filed revenue
The band summarizes business focus and direction. ~ marks estimates.
7 in detail · 11 more below
Brown & Brown Retail
The original business — a network of local offices arranging property, liability, health and personal cover for smaller companies and public bodies. Its own sales, stripped of acquisitions and counting profit-sharing, grew 2.5% last quarter — which management calls not where it wants to be yet.
Competes with Retail brokerage (Gallagher) · US retail platform (Howden) · Commercial Risk (Aon)
In plain English
Picture the insurance agent in a small office who knows every builder and shopkeeper in town, then picture a company built out of many such offices. A customer needs cover for a warehouse, a van fleet, a town council's liabilities; the office finds an insurer willing to write it.
The insurer — not the customer — pays that office a percentage of the premium, and pays it again every year the policy renews. So the money rises and falls with the price of insurance, which these offices do not set. That is how one year can bring far more revenue and barely any new business.
Employee Benefits & Pharmacy Consulting
The health-plan side of Retail: buying company medical cover and advising on the drug bill. Medical costs climbing 8–10% a year lift demand, but changing how the pharmacy advice is charged for knocked about six-tenths of a point off Retail's growth last quarter.
Competes with Health Solutions (Aon) · Health & benefits consulting (WTW)
In plain English
Every employer that offers staff health cover has to buy it from someone, and the bill climbs every year. This is the desk that picks the plan, negotiates it, and increasingly argues over the drug half of the bill — which prescriptions a plan pays for, and at what price.
Payment arrives two ways: a slice of the premium from the insurer, and flat fees for advice and administration. Rising medical costs are oddly good news here, because bigger premiums mean bigger commissions. The company has just put a single leader over the whole North American benefits business.
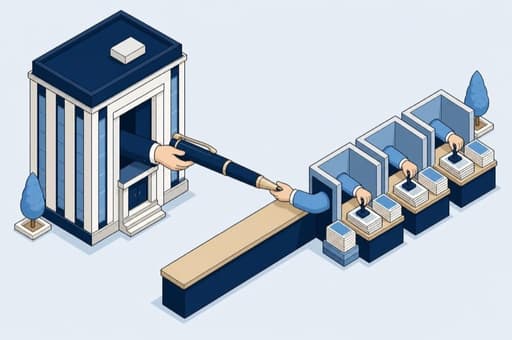
Arrowhead Programs
Insurers hand over the pen: specialist underwriting teams design, price and issue niche policies themselves — over a hundred of them across the Arrowhead units, placing about $20 billion of premium a year. Highest-margin part of the company, and the most exposed to catastrophe prices now falling 15–35%.
Competes with Underwriting Managers (Ryan Specialty) · Program underwriting units (Amwins)
In plain English
Normally the insurer decides who gets a policy and what it costs. Here the insurer hands that pen to Brown & Brown for a narrow corner of the market it does not want to learn itself, and specialist teams write policies in the insurer's name. Across the company's Arrowhead units there are more than a hundred such teams, placing about twenty billion dollars of premium a year.
They earn a commission on every policy, plus a bonus if the batch they wrote turns out to have few claims, so a heavy storm season takes money off the table. No single buyer matters much: the biggest customer on the specialty side is roughly seven percent of its commissions, and goes unnamed.
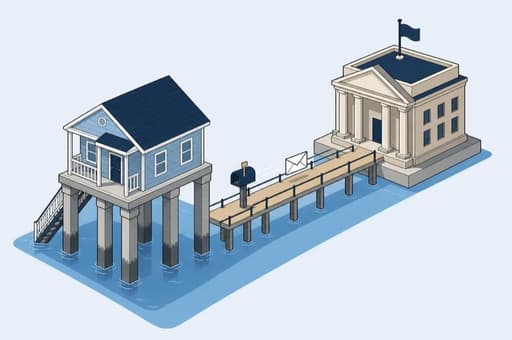
Wright Flood
Flood policies written under the federal program. It collected about $1.1 billion of premium in 2025, passed all of it to FEMA, and kept an allowance just under 30 cents on the dollar — a rate the government has since trimmed.
Competes with Flood insurance (Assurant) · Neptune Flood (Neptune Insurance Holdings)
In plain English
Ordinary home insurance does not pay for a flood; in the United States a federal program run by the disaster agency FEMA does, and private firms do the selling and the paperwork. Wright Flood is a licensed insurer that keeps none of the risk — every premium dollar goes to the government, which pays back a fixed share of it to cover the work. Some seventeen thousand independent agencies sell the policies.
Simple, and exposed: trim that share and the same policies earn less, let the program lapse in Washington and nobody can write a new one. Flood cover on ordinary insurers' paper is the way out, and a private-flood platform was bought in late 2025.
Risk Strategies
The retail half — and the larger half — of the $9.8 billion Accession purchase, closed August 2025 and folded into Retail. Accession as a whole brings about $1.7 billion of annual revenue and $30–40 million of promised savings this year; holding on to its people is the job.
Competes with Specialty retail brokerage (Gallagher) · Specialty retail units (Aon) · Howden US (Howden Group)
In plain English
Buying other brokers is the house habit — dozens of small ones a year — and in 2025 the company swallowed one the size of a rival. Accession's retail half trades as Risk Strategies and handles complicated accounts rather than corner-shop ones. The price was about nine and three-quarter billion dollars, covered roughly half by issuing new shares and half by borrowing.
A brokerage is mostly its people and the clients who follow them, so a purchase like this can leak. Around 275 staff left for Howden, a broker building a US arm from scratch, taking about twenty-three million dollars of customer revenue; a court order followed in May 2026.
Bridge Specialty Group
The wholesale desk: when an agent's own insurers will not touch a risk, Bridge finds one that will, reaching the Lloyd's market through its London arm. Falling property prices are pushing some of that business back to ordinary insurers.
Competes with Amwins Brokerage (Amwins) · RT Specialty (Ryan Specialty)
In plain English
Most insurance is sold off a standard price list. Risks that do not fit — odd trades, bad claims histories, buildings in hurricane country — go to a second market where insurers write their own terms, and only specialists can knock on those doors. Bridge is that specialist, working for other agents rather than for the customer directly.
It takes a cut of the premium from whichever insurer it finds, and on some business it holds the insurer's pen itself. Its London arm reaches Lloyd's, the market where syndicates of insurers club together on awkward risks. The snag: property prices are falling hard enough that some of these risks no longer need a specialist at all.
Arrowhead Specialty
The division created in 2025 out of what was left of One80 — travel and accident cover, warranties, benefits, captives, reinsurance. Priced off medical and injury costs rather than storms, it is meant as ballast; building the same capabilities in Europe is costing margin.
Competes with Group Benefits and specialty units (Amwins) · Affinity and warranty programs (Assurant)
In plain English
A collection of small businesses with nothing in common but how they earn. One team designs the accident cover sold through a membership club, another runs warranty programs, another sets up and administers captives — the private insurance companies employers create to insure themselves.
Each niche holds its own authority from an insurer to write policies, and its own share of the profit when claims stay low. None is large, and that is rather the point: this is the part of the company that does not much care whether the hurricane season is bad, gathered together as ballast against the parts that do.


 Brown & Brown RetailThe original business — a network of local offices arranging property, liability, health and personal cover for smaller companies and public bodies. Its own sales, stripped of acquisitions and counting profit-sharing, grew 2.5% last quarter — which management calls not where it wants to be yet.
The original business — a network of local offices arranging property, liability, health and personal cover for smaller companies and public bodies. Its own sales, stripped of acquisitions and counting profit-sharing, grew 2.5% last quarter — which management calls not where it wants to be yet.
In plain English
Picture the insurance agent in a small office who knows every builder and shopkeeper in town, then picture a company built out of many such offices. A customer needs cover for a warehouse, a van fleet, a town council's liabilities; the office finds an insurer willing to write it.
The insurer — not the customer — pays that office a percentage of the premium, and pays it again every year the policy renews. So the money rises and falls with the price of insurance, which these offices do not set. That is how one year can bring far more revenue and barely any new business.
Competes with Retail brokerage (Gallagher) · US retail platform (Howden) · Commercial Risk (Aon)
 Employee Benefits & Pharmacy ConsultingThe health-plan side of Retail: buying company medical cover and advising on the drug bill. Medical costs climbing 8–10% a year lift demand, but changing how the pharmacy advice is charged for knocked about six-tenths of a point off Retail's growth last quarter.
The health-plan side of Retail: buying company medical cover and advising on the drug bill. Medical costs climbing 8–10% a year lift demand, but changing how the pharmacy advice is charged for knocked about six-tenths of a point off Retail's growth last quarter.
In plain English
Every employer that offers staff health cover has to buy it from someone, and the bill climbs every year. This is the desk that picks the plan, negotiates it, and increasingly argues over the drug half of the bill — which prescriptions a plan pays for, and at what price.
Payment arrives two ways: a slice of the premium from the insurer, and flat fees for advice and administration. Rising medical costs are oddly good news here, because bigger premiums mean bigger commissions. The company has just put a single leader over the whole North American benefits business.
Competes with Health Solutions (Aon) · Health & benefits consulting (WTW)
 Arrowhead ProgramsInsurers hand over the pen: specialist underwriting teams design, price and issue niche policies themselves — over a hundred of them across the Arrowhead units, placing about $20 billion of premium a year. Highest-margin part of the company, and the most exposed to catastrophe prices now falling 15–35%.
Insurers hand over the pen: specialist underwriting teams design, price and issue niche policies themselves — over a hundred of them across the Arrowhead units, placing about $20 billion of premium a year. Highest-margin part of the company, and the most exposed to catastrophe prices now falling 15–35%.
In plain English
Normally the insurer decides who gets a policy and what it costs. Here the insurer hands that pen to Brown & Brown for a narrow corner of the market it does not want to learn itself, and specialist teams write policies in the insurer's name. Across the company's Arrowhead units there are more than a hundred such teams, placing about twenty billion dollars of premium a year.
They earn a commission on every policy, plus a bonus if the batch they wrote turns out to have few claims, so a heavy storm season takes money off the table. No single buyer matters much: the biggest customer on the specialty side is roughly seven percent of its commissions, and goes unnamed.
Competes with Underwriting Managers (Ryan Specialty) · Program underwriting units (Amwins)
 Wright FloodFlood policies written under the federal program. It collected about $1.1 billion of premium in 2025, passed all of it to FEMA, and kept an allowance just under 30 cents on the dollar — a rate the government has since trimmed.
Flood policies written under the federal program. It collected about $1.1 billion of premium in 2025, passed all of it to FEMA, and kept an allowance just under 30 cents on the dollar — a rate the government has since trimmed.
In plain English
Ordinary home insurance does not pay for a flood; in the United States a federal program run by the disaster agency FEMA does, and private firms do the selling and the paperwork. Wright Flood is a licensed insurer that keeps none of the risk — every premium dollar goes to the government, which pays back a fixed share of it to cover the work. Some seventeen thousand independent agencies sell the policies.
Simple, and exposed: trim that share and the same policies earn less, let the program lapse in Washington and nobody can write a new one. Flood cover on ordinary insurers' paper is the way out, and a private-flood platform was bought in late 2025.
Competes with Flood insurance (Assurant) · Neptune Flood (Neptune Insurance Holdings)
 Risk StrategiesThe retail half — and the larger half — of the $9.8 billion Accession purchase, closed August 2025 and folded into Retail. Accession as a whole brings about $1.7 billion of annual revenue and $30–40 million of promised savings this year; holding on to its people is the job.
The retail half — and the larger half — of the $9.8 billion Accession purchase, closed August 2025 and folded into Retail. Accession as a whole brings about $1.7 billion of annual revenue and $30–40 million of promised savings this year; holding on to its people is the job.
In plain English
Buying other brokers is the house habit — dozens of small ones a year — and in 2025 the company swallowed one the size of a rival. Accession's retail half trades as Risk Strategies and handles complicated accounts rather than corner-shop ones. The price was about nine and three-quarter billion dollars, covered roughly half by issuing new shares and half by borrowing.
A brokerage is mostly its people and the clients who follow them, so a purchase like this can leak. Around 275 staff left for Howden, a broker building a US arm from scratch, taking about twenty-three million dollars of customer revenue; a court order followed in May 2026.
Competes with Specialty retail brokerage (Gallagher) · Specialty retail units (Aon) · Howden US (Howden Group)
 Bridge Specialty GroupThe wholesale desk: when an agent's own insurers will not touch a risk, Bridge finds one that will, reaching the Lloyd's market through its London arm. Falling property prices are pushing some of that business back to ordinary insurers.
The wholesale desk: when an agent's own insurers will not touch a risk, Bridge finds one that will, reaching the Lloyd's market through its London arm. Falling property prices are pushing some of that business back to ordinary insurers.
In plain English
Most insurance is sold off a standard price list. Risks that do not fit — odd trades, bad claims histories, buildings in hurricane country — go to a second market where insurers write their own terms, and only specialists can knock on those doors. Bridge is that specialist, working for other agents rather than for the customer directly.
It takes a cut of the premium from whichever insurer it finds, and on some business it holds the insurer's pen itself. Its London arm reaches Lloyd's, the market where syndicates of insurers club together on awkward risks. The snag: property prices are falling hard enough that some of these risks no longer need a specialist at all.
Competes with Amwins Brokerage (Amwins) · RT Specialty (Ryan Specialty)
 Arrowhead SpecialtyThe division created in 2025 out of what was left of One80 — travel and accident cover, warranties, benefits, captives, reinsurance. Priced off medical and injury costs rather than storms, it is meant as ballast; building the same capabilities in Europe is costing margin.
The division created in 2025 out of what was left of One80 — travel and accident cover, warranties, benefits, captives, reinsurance. Priced off medical and injury costs rather than storms, it is meant as ballast; building the same capabilities in Europe is costing margin.
In plain English
A collection of small businesses with nothing in common but how they earn. One team designs the accident cover sold through a membership club, another runs warranty programs, another sets up and administers captives — the private insurance companies employers create to insure themselves.
Each niche holds its own authority from an insurer to write policies, and its own share of the profit when claims stay low. None is large, and that is rather the point: this is the part of the company that does not much care whether the hurricane season is bad, gathered together as ballast against the parts that do.
Competes with Group Benefits and specialty units (Amwins) · Affinity and warranty programs (Assurant)
Named in filings, launches and programs
- Brown & Brown Dealer ServicesServiceWarranty and service-contract programs sold through car, RV and boat dealerships — the one Retail line that rides vehicle sales rather than insurance prices.
- Bridge Specialty InternationalPlatformLondon arm holding Lonmar Global Risks, Decus and BdB since 2025. Britain, the only country outside America reported separately, is near a tenth of revenue.
- Arrowhead IntermediariesPlatformThe August 2025 banner raised over the three specialty divisions, bringing 7,000-plus professionals under one name.
- Oxford Risk Management GroupServiceDesigns and runs captives — the in-house insurance companies employers set up to carry their own risk. Sits inside Arrowhead Specialty.
- Brown & Brown captive facilitiesServiceInsurance pools the company itself participates in; a quiet 2025 storm season meant few claims, which flattered segment margins.
- Quintes HoldingBrandDutch retail broker bought in late 2024; roughly sixty percent of its revenue lands in the first quarter, lumping up the March numbers.
- Poulton AssociatesBrand · RampingPrivate-flood platform bought by Wright Flood in November 2025 — flood cover written on ordinary insurers' paper instead of the federal program.
- Investment income on client moneyServicePremiums sit briefly in the company's hands between customer and insurer; interest on that cash was about $139 million in 2025 and is falling with rates.
- Profit-sharing commissionsServiceBonuses insurers pay when the policies placed for them turn out cheap in claims — over $250 million in 2025, and they rise as claims fall.
- AI-first transformation programProduct · AnnouncedAnthropic's Claude, with McKinsey and Accenture, to be rolled out across roughly 23,000 teammates; management says it is not calling out extra technology spending.
- Pennsylvania wholesale tuck-inBrandA January 2026 Bridge Specialty purchase, typical of the roughly six small agencies bought each quarter.
Brown & Brown Dealer ServicesService
Warranty and service-contract programs sold through car, RV and boat dealerships — the one Retail line that rides vehicle sales rather than insurance prices.
Bridge Specialty InternationalPlatform
London arm holding Lonmar Global Risks, Decus and BdB since 2025. Britain, the only country outside America reported separately, is near a tenth of revenue.
Arrowhead IntermediariesPlatform
The August 2025 banner raised over the three specialty divisions, bringing 7,000-plus professionals under one name.
Oxford Risk Management GroupService
Designs and runs captives — the in-house insurance companies employers set up to carry their own risk. Sits inside Arrowhead Specialty.
Brown & Brown captive facilitiesService
Insurance pools the company itself participates in; a quiet 2025 storm season meant few claims, which flattered segment margins.
Quintes HoldingBrand
Dutch retail broker bought in late 2024; roughly sixty percent of its revenue lands in the first quarter, lumping up the March numbers.
Poulton AssociatesBrand · Ramping
Private-flood platform bought by Wright Flood in November 2025 — flood cover written on ordinary insurers' paper instead of the federal program.
Investment income on client moneyService
Premiums sit briefly in the company's hands between customer and insurer; interest on that cash was about $139 million in 2025 and is falling with rates.
Profit-sharing commissionsService
Bonuses insurers pay when the policies placed for them turn out cheap in claims — over $250 million in 2025, and they rise as claims fall.
AI-first transformation programProduct · Announced
Anthropic's Claude, with McKinsey and Accenture, to be rolled out across roughly 23,000 teammates; management says it is not calling out extra technology spending.
Pennsylvania wholesale tuck-inBrand
A January 2026 Bridge Specialty purchase, typical of the roughly six small agencies bought each quarter.