
Capital One (COF)
Credit-card bank operating Discover payment networks and Brex business-finance software.
Something off on this page? Send us feedback.
Capital One is a bank whose real engine is American credit cards, funded largely by customer deposits. Buying Discover added more borrowers, more savings accounts and a payment network of its own; buying Brex added a business-spending platform. The next chapter is about stitching those additions into the card machine without letting bad loans swallow the gains.
Item facts: FY2025 · year ended Dec 31, 2025, from filings, earnings calls and company pages.
Judgment weights, not filed revenue
The band summarizes business focus and direction. ~ marks estimates.
8 in detail · 12 more below
Domestic Card
The main engine: U.S. consumer and small-business cards produced $37.322 billion of FY2025 revenue. The watch is whether interest and purchase fees stay ahead of funding, rewards, fraud and unpaid balances.
Competes with Sapphire and Freedom cards (JPMorgan Chase) · Platinum and Blue Cash cards (American Express)
In plain English
When someone buys groceries with a Capital One or Discover card, Capital One pays the store first. The customer may repay immediately or carry the balance; carried balances earn interest, while purchases and account fees add smaller streams of money.
Think of it as a toll bridge that also lends travelers the fare. Deposits supply much of the cash going out, and cardholders and small businesses bring it back with interest. Rewards keep people using the bridge, but missed payments, fraud and the cost of attracting customers can eat through the tolls quickly.
Brex
Acquired in April 2026, Brex brings corporate cards and spending software into the card engine. Capital One said it produces hundreds of millions in revenue, still a small base; watch whether it scales while keeping its team and lending discipline.
Competes with Corporate cards and spend management (Ramp) · Business and Corporate Cards (American Express)
In plain English
A company can hand employees Brex cards, set spending rules and see purchases as they happen instead of chasing paper receipts at month-end. Its software also helps finance teams pay bills and organize travel spending.
Capital One gets more business purchases flowing through cards and can lend against some of that activity. Brex gains the funding and reach of a much larger bank. The appeal is one tidy control panel for company spending; the hard part is growing it without making poor loans or losing the people who built the system.
Capital One Travel
A booking service that makes Capital One cards more useful and harder to replace. Booking activity grew 50% in FY2025; watch whether bringing the technology and travel-supplier relationships in-house improves service without inflating rewards costs.
Competes with Chase Travel (JPMorgan Chase) · American Express Travel (American Express)
In plain English
Flights and hotels sit inside the Capital One app, where cardholders can book trips and spend their reward points. In March 2026, Capital One took direct control of the technology and relationships with travel suppliers.
The service works like a members' booking desk attached to the card. Travel companies provide the seats and rooms, cardholders bring the purchases, and the portal can earn booking income. Its larger job is to persuade people to choose and keep a Capital One card, then use it more often. Better trips help; poor inventory or support can undo that loyalty.
Auto
Dealer-arranged vehicle loans contribute about one dollar in every ten of revenue. New lending grew during FY2025; the watch is whether borrowers keep paying when car values, jobs and household budgets weaken.
Competes with Dealer Services (Ally Financial) · Dealer finance and Drive (Santander)
In plain English
At a car dealership, many buyers need a loan before they can drive away. The dealer can send that application to Capital One, which decides whether to fund the car and what interest rate to charge. People can also check likely terms online or refinance an existing loan.
The bank earns interest as drivers repay month by month. Deposits and borrowed money fund the loans, while the car offers some protection if a borrower stops paying. Profit depends on choosing borrowers well: too cautious and dealers send business elsewhere; too loose and repossessed cars may not cover what is owed.
Retail Banking (Capital One 360)
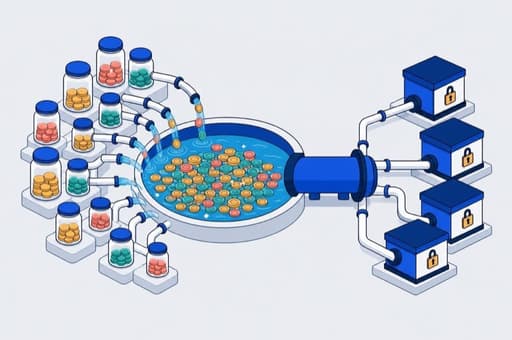
Checking, savings and time-locked savings accounts are an estimated eight cents of each revenue dollar, but their bigger job is supplying dependable money for loans. Watch whether savers stay when Capital One lowers the interest it pays them.
Competes with Online Savings (Ally Financial) · High-Yield Savings (Goldman Sachs)
In plain English
The unglamorous part that feeds almost everything else. Households and small businesses leave money in Capital One 360 checking and savings accounts, using the app, branches, Cafés and cash machines to reach it.
Capital One pays savers interest, then uses much of that pool to fund cards, car loans and business loans at higher rates. The gap helps create earnings. It is like a shared reservoir: many small deposits keep the lending pipes full. Trust, service and a competitive savings rate keep the water from draining to another bank.
Commercial Banking
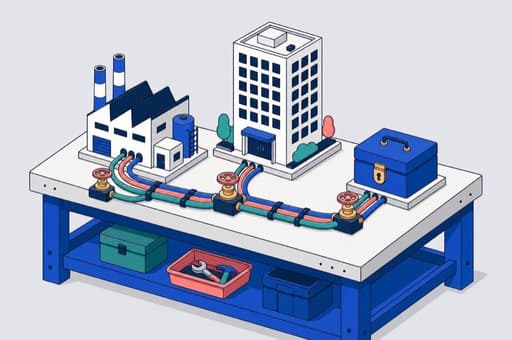
Loans and money-moving services for mid-sized companies produced $3.655 billion of FY2025 revenue. Q2 FY2026 revenue fell 9% from a year earlier even as loans grew, so pricing and fees matter as much as volume.
Competes with Commercial Banking (Wells Fargo) · Global Commercial Banking and CashPro (Bank of America)
In plain English
A growing company may need money for inventory, a new building or the quiet daily work of paying suppliers and collecting from customers. Capital One lends that money and helps move cash in and out of the business.
Interest on loans is the main engine, with fees from payment and financing services alongside it. Picture a sturdy workbench for companies too large for a neighborhood account but smaller than global giants. Capital One gets paid while the work continues; weak customer cash flow, falling property values or too much lending to one industry can turn that income into losses.
International Card Businesses
Capital One cards in Britain and Canada add roughly two cents of each revenue dollar. This is a small extension of the card formula; local consumer rules, currency moves and lending quality decide whether it earns its keep.
Competes with Aqua cards (NewDay) · MBNA cards (Lloyds Banking Group)
In plain English
Across Britain and Canada, customers use Capital One cards to buy things now and repay later. Just as in the United States, the company collects interest when balances remain unpaid and earns money when people use the cards.
This is the same shop under two different sets of house rules. Each country decides how cards may be marketed, priced and collected, while local spending and household finances shape demand. Group funding supports the loans and card networks carry the purchases. The business stays modest because it serves two smaller pools beside the huge American card book.
Global Payment Network
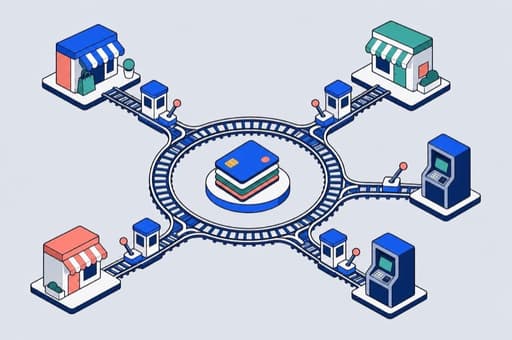
The Discover, PULSE and Diners Club rails carried about $402 billion from the May purchase through year-end. Q2 FY2026 volume rose 9% from the prior quarter; broad merchant acceptance remains the essential test.
Competes with VisaNet (Visa) · Mastercard Network (Mastercard)
In plain English
A card needs roads connecting the buyer's bank, the shop and the shop's bank. Discover brought Capital One its own set of those roads, plus PULSE for debit cards and cash machines and Diners Club partners outside the core footprint.
Whenever a payment travels across the network, Capital One can collect a small fee for routing it safely and quickly. More shops make the network useful to more cardholders; more cardholders make it worth accepting for more shops. That loop is powerful, but Visa and Mastercard already operate vastly larger road systems.


 Domestic CardThe main engine: U.S. consumer and small-business cards produced $37.322 billion of FY2025 revenue. The watch is whether interest and purchase fees stay ahead of funding, rewards, fraud and unpaid balances.
The main engine: U.S. consumer and small-business cards produced $37.322 billion of FY2025 revenue. The watch is whether interest and purchase fees stay ahead of funding, rewards, fraud and unpaid balances.
In plain English
When someone buys groceries with a Capital One or Discover card, Capital One pays the store first. The customer may repay immediately or carry the balance; carried balances earn interest, while purchases and account fees add smaller streams of money.
Think of it as a toll bridge that also lends travelers the fare. Deposits supply much of the cash going out, and cardholders and small businesses bring it back with interest. Rewards keep people using the bridge, but missed payments, fraud and the cost of attracting customers can eat through the tolls quickly.
Competes with Sapphire and Freedom cards (JPMorgan Chase) · Platinum and Blue Cash cards (American Express)
 BrexAcquired in April 2026, Brex brings corporate cards and spending software into the card engine. Capital One said it produces hundreds of millions in revenue, still a small base; watch whether it scales while keeping its team and lending discipline.
Acquired in April 2026, Brex brings corporate cards and spending software into the card engine. Capital One said it produces hundreds of millions in revenue, still a small base; watch whether it scales while keeping its team and lending discipline.
In plain English
A company can hand employees Brex cards, set spending rules and see purchases as they happen instead of chasing paper receipts at month-end. Its software also helps finance teams pay bills and organize travel spending.
Capital One gets more business purchases flowing through cards and can lend against some of that activity. Brex gains the funding and reach of a much larger bank. The appeal is one tidy control panel for company spending; the hard part is growing it without making poor loans or losing the people who built the system.
Competes with Corporate cards and spend management (Ramp) · Business and Corporate Cards (American Express)
 Capital One TravelA booking service that makes Capital One cards more useful and harder to replace. Booking activity grew 50% in FY2025; watch whether bringing the technology and travel-supplier relationships in-house improves service without inflating rewards costs.
A booking service that makes Capital One cards more useful and harder to replace. Booking activity grew 50% in FY2025; watch whether bringing the technology and travel-supplier relationships in-house improves service without inflating rewards costs.
In plain English
Flights and hotels sit inside the Capital One app, where cardholders can book trips and spend their reward points. In March 2026, Capital One took direct control of the technology and relationships with travel suppliers.
The service works like a members' booking desk attached to the card. Travel companies provide the seats and rooms, cardholders bring the purchases, and the portal can earn booking income. Its larger job is to persuade people to choose and keep a Capital One card, then use it more often. Better trips help; poor inventory or support can undo that loyalty.
Competes with Chase Travel (JPMorgan Chase) · American Express Travel (American Express)
 AutoDealer-arranged vehicle loans contribute about one dollar in every ten of revenue. New lending grew during FY2025; the watch is whether borrowers keep paying when car values, jobs and household budgets weaken.
Dealer-arranged vehicle loans contribute about one dollar in every ten of revenue. New lending grew during FY2025; the watch is whether borrowers keep paying when car values, jobs and household budgets weaken.
In plain English
At a car dealership, many buyers need a loan before they can drive away. The dealer can send that application to Capital One, which decides whether to fund the car and what interest rate to charge. People can also check likely terms online or refinance an existing loan.
The bank earns interest as drivers repay month by month. Deposits and borrowed money fund the loans, while the car offers some protection if a borrower stops paying. Profit depends on choosing borrowers well: too cautious and dealers send business elsewhere; too loose and repossessed cars may not cover what is owed.
Competes with Dealer Services (Ally Financial) · Dealer finance and Drive (Santander)
 Retail Banking (Capital One 360)Checking, savings and time-locked savings accounts are an estimated eight cents of each revenue dollar, but their bigger job is supplying dependable money for loans. Watch whether savers stay when Capital One lowers the interest it pays them.
Checking, savings and time-locked savings accounts are an estimated eight cents of each revenue dollar, but their bigger job is supplying dependable money for loans. Watch whether savers stay when Capital One lowers the interest it pays them.
In plain English
The unglamorous part that feeds almost everything else. Households and small businesses leave money in Capital One 360 checking and savings accounts, using the app, branches, Cafés and cash machines to reach it.
Capital One pays savers interest, then uses much of that pool to fund cards, car loans and business loans at higher rates. The gap helps create earnings. It is like a shared reservoir: many small deposits keep the lending pipes full. Trust, service and a competitive savings rate keep the water from draining to another bank.
Competes with Online Savings (Ally Financial) · High-Yield Savings (Goldman Sachs)
 Commercial BankingLoans and money-moving services for mid-sized companies produced $3.655 billion of FY2025 revenue. Q2 FY2026 revenue fell 9% from a year earlier even as loans grew, so pricing and fees matter as much as volume.
Loans and money-moving services for mid-sized companies produced $3.655 billion of FY2025 revenue. Q2 FY2026 revenue fell 9% from a year earlier even as loans grew, so pricing and fees matter as much as volume.
In plain English
A growing company may need money for inventory, a new building or the quiet daily work of paying suppliers and collecting from customers. Capital One lends that money and helps move cash in and out of the business.
Interest on loans is the main engine, with fees from payment and financing services alongside it. Picture a sturdy workbench for companies too large for a neighborhood account but smaller than global giants. Capital One gets paid while the work continues; weak customer cash flow, falling property values or too much lending to one industry can turn that income into losses.
Competes with Commercial Banking (Wells Fargo) · Global Commercial Banking and CashPro (Bank of America)
 International Card BusinessesCapital One cards in Britain and Canada add roughly two cents of each revenue dollar. This is a small extension of the card formula; local consumer rules, currency moves and lending quality decide whether it earns its keep.
Capital One cards in Britain and Canada add roughly two cents of each revenue dollar. This is a small extension of the card formula; local consumer rules, currency moves and lending quality decide whether it earns its keep.
In plain English
Across Britain and Canada, customers use Capital One cards to buy things now and repay later. Just as in the United States, the company collects interest when balances remain unpaid and earns money when people use the cards.
This is the same shop under two different sets of house rules. Each country decides how cards may be marketed, priced and collected, while local spending and household finances shape demand. Group funding supports the loans and card networks carry the purchases. The business stays modest because it serves two smaller pools beside the huge American card book.
Competes with Aqua cards (NewDay) · MBNA cards (Lloyds Banking Group)
 Global Payment NetworkThe Discover, PULSE and Diners Club rails carried about $402 billion from the May purchase through year-end. Q2 FY2026 volume rose 9% from the prior quarter; broad merchant acceptance remains the essential test.
The Discover, PULSE and Diners Club rails carried about $402 billion from the May purchase through year-end. Q2 FY2026 volume rose 9% from the prior quarter; broad merchant acceptance remains the essential test.
In plain English
A card needs roads connecting the buyer's bank, the shop and the shop's bank. Discover brought Capital One its own set of those roads, plus PULSE for debit cards and cash machines and Diners Club partners outside the core footprint.
Whenever a payment travels across the network, Capital One can collect a small fee for routing it safely and quickly. More shops make the network useful to more cardholders; more cardholders make it worth accepting for more shops. That loop is powerful, but Visa and Mastercard already operate vastly larger road systems.
Competes with VisaNet (Visa) · Mastercard Network (Mastercard)
Named in filings, launches and programs
- Personal LoansProduct lineUnsecured loans acquired with Discover; new lending is deliberately muted and expected to bottom around late 2026.
- Venture XBrandPremium travel-rewards card built to attract high-spending customers with fees, rewards and booking benefits.
- SparkBrandSmall-business card family whose economics sit inside Domestic Card.
- Discover itBrandDiscover cash-back card family retained after the acquisition and included in Domestic Card.
- T-Mobile VisaCustomer programCard launched in late 2025 and distributed through T-Mobile's online and store channels.
- Capital One ShoppingServiceShopping and offer-finding service designed to keep consumers engaged; its revenue is not shown separately.
- Auto NavigatorPlatformOnline car-shopping and loan-checking tool that feeds borrowers into the Auto business.
- Capital One SoftwareServiceEnterprise software line that announced Databolt Connect in 2026; no separate revenue is disclosed.
- PULSEEcosystemU.S. debit-card and cash-machine routing system inside the Global Payment Network.
- Diners Club InternationalEcosystemPartner-licensed network that extends payment acceptance beyond Discover's main footprint.
- Network PartnersEcosystemBanks, financial technology companies and other networks that add payment traffic to Capital One's rails.
- Capital One, National AssociationBrandThe principal operating bank and surviving bank entity after Discover Bank was merged into it.
Personal LoansProduct line
Unsecured loans acquired with Discover; new lending is deliberately muted and expected to bottom around late 2026.
Venture XBrand
Premium travel-rewards card built to attract high-spending customers with fees, rewards and booking benefits.
SparkBrand
Small-business card family whose economics sit inside Domestic Card.
Discover itBrand
Discover cash-back card family retained after the acquisition and included in Domestic Card.
T-Mobile VisaCustomer program
Card launched in late 2025 and distributed through T-Mobile's online and store channels.
Capital One ShoppingService
Shopping and offer-finding service designed to keep consumers engaged; its revenue is not shown separately.
Auto NavigatorPlatform
Online car-shopping and loan-checking tool that feeds borrowers into the Auto business.
Capital One SoftwareService
Enterprise software line that announced Databolt Connect in 2026; no separate revenue is disclosed.
PULSEEcosystem
U.S. debit-card and cash-machine routing system inside the Global Payment Network.
Diners Club InternationalEcosystem
Partner-licensed network that extends payment acceptance beyond Discover's main footprint.
Network PartnersEcosystem
Banks, financial technology companies and other networks that add payment traffic to Capital One's rails.
Capital One, National AssociationBrand
The principal operating bank and surviving bank entity after Discover Bank was merged into it.