
KKR (KKR)
Manages private markets and credit alongside Global Atlantic's retirement insurance business.
Something off on this page? Send us feedback.
KKR is a three-part financial machine: it manages other people’s money, owns a large retirement insurer, and keeps selected investments for itself. Global Atlantic now supplies nearly half of business-line revenue, while newer credit, infrastructure, wealth and specialty funds are widening a company once known mainly for buyouts.
Item facts: FY2025 · year ended Dec 31, 2025, from filings, earnings calls and company pages.
Judgment weights, not filed revenue
The band summarizes business focus and direction. ~ marks estimates.
8 in detail · 16 more below
Global Atlantic
Global Atlantic sells retirement income and life protection, then invests the money held for future payouts. Its $7.22B of investment income supplied 47.8% of FY2025 business-line revenue; watch whether investment returns keep outrunning policy costs.
Competes with Athene retirement solutions (Apollo) · Power Series Index Annuity (Corebridge)
In plain English
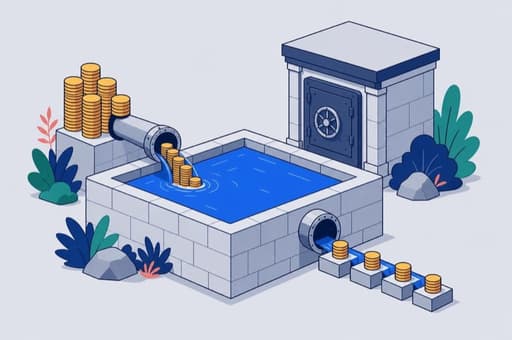
Picture a reservoir that fills before it drains. People pay Global Atlantic now for retirement income or life protection later; pensions and other insurers can also hand it promises they already made. Banks and financial advisers help sell those contracts.
KKR invests the waiting pool across its funds and other assets. Global Atlantic makes money when that investment income stays above customer payouts, sales costs and the cost of keeping the promises. Interest rates, missed debt payments and customers leaving early can narrow that gap.
Private Equity
Funds that buy and improve companies produced $2.95B of fees and sale-time profit shares, equal to 19.5% of FY2025 business-line revenue. The swing factor is whether healthy sale markets let KKR turn paper gains into cash.
Competes with Corporate Private Equity (Blackstone) · Global Private Equity (Carlyle)
In plain English
This is the business behind KKR’s old buyout reputation. Pensions, insurers, governments and wealthy clients pool money with KKR, which buys companies, works with them for years and eventually sells them. Some funds seek control; others hold businesses longer or back companies still growing.
KKR collects a regular fee for running the pool. If a sale clears the agreed profit hurdle, KKR also keeps part of the gain. That second payday can be large, but it waits on the companies performing well and on buyers or stock markets being ready when KKR wants to exit.
KKR Solutions
The newer sports and investment-firm platform grew from about $15B when the Arctos purchase was announced to $20B managed by June 2026. Watch whether league approvals, fair pricing and willing sellers support the next leg.
Competes with Strategic Partners (Blackstone) · GP Strategic Capital (Blue Owl)
In plain English
A sports team owner or investment firm sometimes wants cash without selling everything. KKR Solutions supplies it by buying approved team stakes, pieces of fund managers, or existing fund interests from owners who want out. Arctos, a specialist sports investor KKR bought in 2026, is the anchor.
Institutions put money into these pools and pay KKR to choose and manage the stakes. KKR can also share in gains when holdings are later sold. Growth depends on finding enough acceptable deals: sports leagues control who may own teams, while prices and willing buyers govern trades in existing fund interests.
Credit and Liquid Strategies
KKR’s loan businesses generated $1.66B of fees and paid-out profit shares, or 11.0% of FY2025 business-line revenue. Recurring fees help steady the engine; defaults, recoveries, interest rates and the supply of new loans set the pace.
Competes with Apollo Credit (Apollo) · Blackstone Credit & Insurance (Blackstone)
In plain English
Instead of buying a company, this side often lends to it—or buys loans someone else made. It covers loans to debt-heavy businesses, privately negotiated company loans, and financing backed by things such as consumer payments, equipment or other dependable cash flows.
Pensions, insurers and other clients supply the money and pay KKR to find, price and manage the loans. Global Atlantic supplies a lasting pool of insurance money too. KKR earns management fees and can share in investment gains, but borrowers missing payments can erase part of the return.
Infrastructure
Power, data-center, transport, utility and climate investments contributed roughly 6.4% of FY2025 business-line revenue. Demand is substantial, but permits, grid connections, construction costs and signed users decide whether planned assets become paying ones.
Competes with Blackstone Infrastructure (Blackstone) · Brookfield Infrastructure (Brookfield)
In plain English
These are the systems people and businesses use without thinking about who owns them: power plants and wires, data centers, transport links and utilities. KKR gathers long-term money from investors, then buys, builds or lends against those assets.
Users such as power customers, governments, shippers and building tenants create the cash that supports each project. KKR charges investors for managing the pool and may share in gains when an asset is sold. Its newer digital push also leans on ECP and Vistra, power specialists, because a data center is useless without dependable electricity.
Real Estate
Property funds and property loans contributed roughly 4.5% of FY2025 business-line revenue. Occupancy, rents, loan payments and the ability to replace old debt or sell buildings determine whether this smaller engine pays steadily or stalls.
Competes with Blackstone Real Estate (Blackstone) · Brookfield Real Estate (Brookfield)
In plain English
Here KKR wears two hats. With one, its funds buy offices, apartments, warehouses and other properties. With the other, they lend to property owners and developers. Institutions and eligible individual investors provide the money and pay KKR to put it to work.
Tenants supply rent; borrowers supply interest and repay the loan. KKR earns its management fee along the way and may take part of the profit when a building or loan is sold. Empty space, falling rents or expensive refinancing can weaken both sides at once.
KKR Capital Markets
The deal-financing desk earned $930M of fees, equal to 6.2% of FY2025 business-line revenue. Debt arrangements supplied 85% of Q2 2026 fees, so open lending markets and a healthy flow of company sales matter most.
Competes with Capital Solutions (Apollo) · Global Capital Markets (Carlyle)
In plain English
When a company needs a large loan or wants to sell shares, finding enough willing buyers is a job of its own. KKR Capital Markets designs the financing, brings banks and other lenders together, places the debt or shares, and advises on the deal.
Portfolio companies are a natural source of work, but outside companies hire the desk too. They pay a fee when the financing or transaction closes. That makes this less like a monthly subscription and more like a busy tollbooth: money arrives when deals can get through.
Strategic Holdings
Long-held company stakes sent KKR $232M in dividends and sale gains, equal to 1.5% of FY2025 business-line revenue. What matters is how much cash the businesses can distribute and when KKR can sell well.
Competes with Brookfield operating businesses (Brookfield) · Berkshire operating companies (Berkshire Hathaway)
In plain English
The unglamorous part that collects cash from companies KKR owns for longer than a normal fund. Rather than charging outside investors, KKR receives dividends when those businesses have spare cash and records gains when it sells a stake.
Think of an orchard: the trees can send fruit every season, but cutting one down for timber is a separate, occasional payday. Employees, suppliers and lenders help each company operate; its customers ultimately fund the cash. Weak business results or a closed sale market can delay what reaches KKR.


 Global AtlanticGlobal Atlantic sells retirement income and life protection, then invests the money held for future payouts. Its $7.22B of investment income supplied 47.8% of FY2025 business-line revenue; watch whether investment returns keep outrunning policy costs.
Global Atlantic sells retirement income and life protection, then invests the money held for future payouts. Its $7.22B of investment income supplied 47.8% of FY2025 business-line revenue; watch whether investment returns keep outrunning policy costs.
In plain English
Picture a reservoir that fills before it drains. People pay Global Atlantic now for retirement income or life protection later; pensions and other insurers can also hand it promises they already made. Banks and financial advisers help sell those contracts.
KKR invests the waiting pool across its funds and other assets. Global Atlantic makes money when that investment income stays above customer payouts, sales costs and the cost of keeping the promises. Interest rates, missed debt payments and customers leaving early can narrow that gap.
Competes with Athene retirement solutions (Apollo) · Power Series Index Annuity (Corebridge)
 Private EquityFunds that buy and improve companies produced $2.95B of fees and sale-time profit shares, equal to 19.5% of FY2025 business-line revenue. The swing factor is whether healthy sale markets let KKR turn paper gains into cash.
Funds that buy and improve companies produced $2.95B of fees and sale-time profit shares, equal to 19.5% of FY2025 business-line revenue. The swing factor is whether healthy sale markets let KKR turn paper gains into cash.
In plain English
This is the business behind KKR’s old buyout reputation. Pensions, insurers, governments and wealthy clients pool money with KKR, which buys companies, works with them for years and eventually sells them. Some funds seek control; others hold businesses longer or back companies still growing.
KKR collects a regular fee for running the pool. If a sale clears the agreed profit hurdle, KKR also keeps part of the gain. That second payday can be large, but it waits on the companies performing well and on buyers or stock markets being ready when KKR wants to exit.
Competes with Corporate Private Equity (Blackstone) · Global Private Equity (Carlyle)
 KKR SolutionsThe newer sports and investment-firm platform grew from about $15B when the Arctos purchase was announced to $20B managed by June 2026. Watch whether league approvals, fair pricing and willing sellers support the next leg.
The newer sports and investment-firm platform grew from about $15B when the Arctos purchase was announced to $20B managed by June 2026. Watch whether league approvals, fair pricing and willing sellers support the next leg.
In plain English
A sports team owner or investment firm sometimes wants cash without selling everything. KKR Solutions supplies it by buying approved team stakes, pieces of fund managers, or existing fund interests from owners who want out. Arctos, a specialist sports investor KKR bought in 2026, is the anchor.
Institutions put money into these pools and pay KKR to choose and manage the stakes. KKR can also share in gains when holdings are later sold. Growth depends on finding enough acceptable deals: sports leagues control who may own teams, while prices and willing buyers govern trades in existing fund interests.
Competes with Strategic Partners (Blackstone) · GP Strategic Capital (Blue Owl)
 Credit and Liquid StrategiesKKR’s loan businesses generated $1.66B of fees and paid-out profit shares, or 11.0% of FY2025 business-line revenue. Recurring fees help steady the engine; defaults, recoveries, interest rates and the supply of new loans set the pace.
KKR’s loan businesses generated $1.66B of fees and paid-out profit shares, or 11.0% of FY2025 business-line revenue. Recurring fees help steady the engine; defaults, recoveries, interest rates and the supply of new loans set the pace.
In plain English
Instead of buying a company, this side often lends to it—or buys loans someone else made. It covers loans to debt-heavy businesses, privately negotiated company loans, and financing backed by things such as consumer payments, equipment or other dependable cash flows.
Pensions, insurers and other clients supply the money and pay KKR to find, price and manage the loans. Global Atlantic supplies a lasting pool of insurance money too. KKR earns management fees and can share in investment gains, but borrowers missing payments can erase part of the return.
Competes with Apollo Credit (Apollo) · Blackstone Credit & Insurance (Blackstone)
 InfrastructurePower, data-center, transport, utility and climate investments contributed roughly 6.4% of FY2025 business-line revenue. Demand is substantial, but permits, grid connections, construction costs and signed users decide whether planned assets become paying ones.
Power, data-center, transport, utility and climate investments contributed roughly 6.4% of FY2025 business-line revenue. Demand is substantial, but permits, grid connections, construction costs and signed users decide whether planned assets become paying ones.
In plain English
These are the systems people and businesses use without thinking about who owns them: power plants and wires, data centers, transport links and utilities. KKR gathers long-term money from investors, then buys, builds or lends against those assets.
Users such as power customers, governments, shippers and building tenants create the cash that supports each project. KKR charges investors for managing the pool and may share in gains when an asset is sold. Its newer digital push also leans on ECP and Vistra, power specialists, because a data center is useless without dependable electricity.
Competes with Blackstone Infrastructure (Blackstone) · Brookfield Infrastructure (Brookfield)
 Real EstateProperty funds and property loans contributed roughly 4.5% of FY2025 business-line revenue. Occupancy, rents, loan payments and the ability to replace old debt or sell buildings determine whether this smaller engine pays steadily or stalls.
Property funds and property loans contributed roughly 4.5% of FY2025 business-line revenue. Occupancy, rents, loan payments and the ability to replace old debt or sell buildings determine whether this smaller engine pays steadily or stalls.
In plain English
Here KKR wears two hats. With one, its funds buy offices, apartments, warehouses and other properties. With the other, they lend to property owners and developers. Institutions and eligible individual investors provide the money and pay KKR to put it to work.
Tenants supply rent; borrowers supply interest and repay the loan. KKR earns its management fee along the way and may take part of the profit when a building or loan is sold. Empty space, falling rents or expensive refinancing can weaken both sides at once.
Competes with Blackstone Real Estate (Blackstone) · Brookfield Real Estate (Brookfield)
 KKR Capital MarketsThe deal-financing desk earned $930M of fees, equal to 6.2% of FY2025 business-line revenue. Debt arrangements supplied 85% of Q2 2026 fees, so open lending markets and a healthy flow of company sales matter most.
The deal-financing desk earned $930M of fees, equal to 6.2% of FY2025 business-line revenue. Debt arrangements supplied 85% of Q2 2026 fees, so open lending markets and a healthy flow of company sales matter most.
In plain English
When a company needs a large loan or wants to sell shares, finding enough willing buyers is a job of its own. KKR Capital Markets designs the financing, brings banks and other lenders together, places the debt or shares, and advises on the deal.
Portfolio companies are a natural source of work, but outside companies hire the desk too. They pay a fee when the financing or transaction closes. That makes this less like a monthly subscription and more like a busy tollbooth: money arrives when deals can get through.
Competes with Capital Solutions (Apollo) · Global Capital Markets (Carlyle)
 Strategic HoldingsLong-held company stakes sent KKR $232M in dividends and sale gains, equal to 1.5% of FY2025 business-line revenue. What matters is how much cash the businesses can distribute and when KKR can sell well.
Long-held company stakes sent KKR $232M in dividends and sale gains, equal to 1.5% of FY2025 business-line revenue. What matters is how much cash the businesses can distribute and when KKR can sell well.
In plain English
The unglamorous part that collects cash from companies KKR owns for longer than a normal fund. Rather than charging outside investors, KKR receives dividends when those businesses have spare cash and records gains when it sells a stake.
Think of an orchard: the trees can send fruit every season, but cutting one down for timber is a separate, occasional payday. Employees, suppliers and lenders help each company operate; its customers ultimately fund the cash. Weak business results or a closed sale market can delay what reaches KKR.
Competes with Brookfield operating businesses (Brookfield) · Berkshire operating companies (Berkshire Hathaway)
Named in filings, launches and programs
- Principal ActivitiesServiceKKR’s own money invested alongside clients and later sales generated $403M, or 2.7% of FY2025 business-line revenue.
- K-SeriesEcosystem · RampingIndividual-investor funds with limited periodic withdrawals grew from $16B managed at 2024 year-end to $42B by June 2026.
- Fore annuity familyProduct lineGlobal Atlantic’s menu of retirement contracts offers fixed returns, market-linked growth or income for individual savers.
- Ivy and other sponsored reinsurance vehiclesPlatformOutside investors add capacity to back insurance promises through these vehicles; they held $62B managed in June 2026.
- Helix Digital InfrastructurePlatform · AnnouncedPlanned data-center and power company backed by more than $10B of initial commitments; paying tenants were not yet disclosed.
- KKR–ECP strategic partnershipCustomer program$50B program to develop data centers and power supply; the large technology customers behind demand remain unnamed.
- Asset-Based FinanceProduct line$91B of privately arranged loans backed by consumer payments, physical assets or contracted cash flows.
- Corporate Private Credit / Direct LendingProduct line$48B of privately negotiated company loans, including $39B lent directly rather than bought in public markets.
- Leveraged CreditProduct line$143B in loans and lower-rated bonds from debt-heavy companies, plus managed bundles of similar loans.
- Strategic InvestmentsProduct line$11B pool for unusual credit opportunities and companies that need tailored financing.
- Traditional Private EquityProduct lineKKR’s large traditional funds buy controlling stakes in companies and aim to improve them before an eventual sale.
- Core Private EquityProduct lineLonger-hold company ownership for businesses meant to grow in value and send cash back over more years.
- Kuwait Oil Company pipeline partnershipCustomer programKKR joined Blackstone and Brookfield in a $16B deal to lease Kuwait’s oil pipelines and rent them back to Kuwait Oil Company.
- KKR Real Estate Select Trust (KREST)ProductA property-investment vehicle built for eligible individuals, designed to stay open rather than end on a fixed fund date.
- KKR Real Estate Finance Trust (KREF)BrandA separately listed commercial-property lender managed by KKR.
- Energy Real AssetsProduct lineEnergy investments beyond the named infrastructure and property totals accounted for about $8B managed in June 2026.
Principal ActivitiesService
KKR’s own money invested alongside clients and later sales generated $403M, or 2.7% of FY2025 business-line revenue.
K-SeriesEcosystem · Ramping
Individual-investor funds with limited periodic withdrawals grew from $16B managed at 2024 year-end to $42B by June 2026.
Fore annuity familyProduct line
Global Atlantic’s menu of retirement contracts offers fixed returns, market-linked growth or income for individual savers.
Ivy and other sponsored reinsurance vehiclesPlatform
Outside investors add capacity to back insurance promises through these vehicles; they held $62B managed in June 2026.
Helix Digital InfrastructurePlatform · Announced
Planned data-center and power company backed by more than $10B of initial commitments; paying tenants were not yet disclosed.
KKR–ECP strategic partnershipCustomer program
$50B program to develop data centers and power supply; the large technology customers behind demand remain unnamed.
Asset-Based FinanceProduct line
$91B of privately arranged loans backed by consumer payments, physical assets or contracted cash flows.
Corporate Private Credit / Direct LendingProduct line
$48B of privately negotiated company loans, including $39B lent directly rather than bought in public markets.
Leveraged CreditProduct line
$143B in loans and lower-rated bonds from debt-heavy companies, plus managed bundles of similar loans.
Strategic InvestmentsProduct line
$11B pool for unusual credit opportunities and companies that need tailored financing.
Traditional Private EquityProduct line
KKR’s large traditional funds buy controlling stakes in companies and aim to improve them before an eventual sale.
Core Private EquityProduct line
Longer-hold company ownership for businesses meant to grow in value and send cash back over more years.
Kuwait Oil Company pipeline partnershipCustomer program
KKR joined Blackstone and Brookfield in a $16B deal to lease Kuwait’s oil pipelines and rent them back to Kuwait Oil Company.
KKR Real Estate Select Trust (KREST)Product
A property-investment vehicle built for eligible individuals, designed to stay open rather than end on a fixed fund date.
KKR Real Estate Finance Trust (KREF)Brand
A separately listed commercial-property lender managed by KKR.
Energy Real AssetsProduct line
Energy investments beyond the named infrastructure and property totals accounted for about $8B managed in June 2026.