
M&T Bank (MTB)
Regional commercial and retail banking with Wilmington Trust wealth and institutional services.
Something off on this page? Send us feedback.
M&T is a Buffalo-headquartered bank with branches running from Maine to Virginia. Most of what it earns is the plain difference between what it pays savers and what it charges borrowers; the rest is fees for looking after other people's money and other people's loans. After two careful years of shrinking its property lending and cleaning up problem borrowers, it has turned back toward growth.
Item facts: FY2025 · year ended Dec 31, 2025, from filings, earnings calls and company pages.
Judgment weights, not filed revenue
The band summarizes business focus and direction. ~ marks estimates.
7 in detail · 14 more below
Retail Bank
Roughly 900 branches from Maine to Virginia, plus everyday accounts, small-business banking and consumer loans. Half of all revenue — $4.87B in 2025 — but it earned less than the year before as rate cuts shrank the value of its cheap deposits.
Competes with Chase consumer branches (JPMorgan) · Citizens consumer bank (Citizens Financial Group) · TD Bank US retail branches (TD Bank)
In plain English
This is the part with a front door. People and small businesses keep their spending money in accounts at an M&T branch, and the bank pays them little or nothing for it — $43.9B sits in accounts paying no interest at all. That money is lent back out at much higher rates, and the gap between the two is the profit.
When interest rates fall, the money a bank makes simply from holding cheap deposits shrinks. That is why this half earned less last year than the year before — revenue $4.87B against $5.10B — while the commercial side grew.
Auto, recreational and home-equity lending
Car, camper, boat and home-equity loans — the vehicle paper largely written at dealerships and handed to M&T. $12.15B of car loans, $7.93B of home equity, $3.72B of recreational vehicles and boats, and the book is growing.
Competes with LightStream recreational and marine loans (Truist) · Auto finance (Ally Financial)
In plain English
Buy a car, an RV or a boat and the dealer usually arranges the loan right there at the desk. M&T is one of the banks behind that desk: it takes the loan onto its books, and the customer pays it back with interest for years. Home-equity lines work the other way round — a homeowner borrows against the value of the house.
It is a volume business, so the money is made on the interest and lost on repossession: when used cars and used boats fetch less, the loss on a loan that goes bad is bigger. Bank-wide, losses ran at about 23 cents per hundred dollars of loans last quarter.
Residential mortgage sub-servicing
M&T collects and administers other companies' home loans for a fee, owning none of them. Lakeview moved a batch across in June 2026, guided to $30–40M a year at about half margin from the third quarter.
Competes with Mr. Cooper sub-servicing platform (Rocket) · Sub-servicing (Cenlar)
In plain English
Somebody has to take the monthly mortgage payment, chase it when it is late, hold the tax and insurance money and send the statements. Lenders hire that job out. M&T does it for Lakeview Loan Servicing, a mortgage company, and for firms related to it — they pay a fee per loan, and M&T carries none of the mortgages itself.
As management put it, "they just pay us a fee to service those loans… there's nothing to hedge." Dull, steady work: the newest batch, moved across from the rival servicer Mr. Cooper in June 2026, was guided to $30–40M a year at roughly half margin.
Commercial Bank
Loans and banking for mid-sized and large companies in M&T's own states: $2.95B of revenue in 2025 and $66.0B of business loans by mid-2026. This is the side that is growing — fees rose 18% in a year.
Competes with KeyBank commercial banking (KeyBank) · Fifth Third commercial banking (Fifth Third) · Huntington commercial banking (Huntington)
In plain English
Think of the companies on a regional main street that are too big for a small-business loan and too small for Wall Street — a manufacturer, a hospital group, a property developer. This is the bank they call. M&T lends them money, holds their working cash, and charges for arranging the larger deals.
It is now the growing side of the house. Business loans reached $66.0B by mid-2026, with new money going to mid-sized companies, to lenders who need short-term funding, and to large institutional property borrowers. Fees grew 18% over the year, and money set aside for loans that might sour fell to $23M in the quarter from $60M.
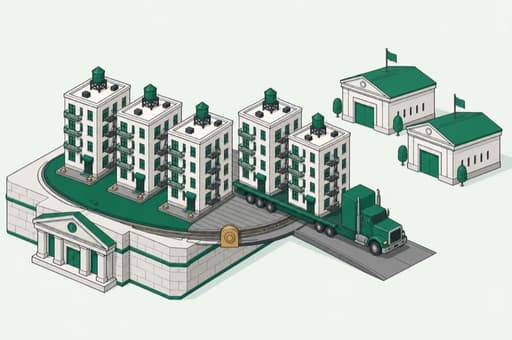
Commercial real estate platform
Lending against apartment blocks and offices — $24.5B on the books, $7.12B of it apartments — plus M&T Realty Capital, which writes loans and passes them to Fannie Mae and Freddie Mac. It grew in 2026 for the first time since 2021.
Competes with Fannie Mae agency multifamily lending (Walker & Dunlop) · Freddie Mac multifamily lending (Berkadia)
In plain English
Two ways to lend on a building. M&T can keep the loan and collect the interest, or, through M&T Realty Capital, write it and pass it to the government-backed housing lenders Fannie Mae and Freddie Mac, taking a fee and keeping the job of collecting the payments — it looks after more than 1,500 such loans, over $28B worth.
In 2025 it wrote as much for sale as it kept. After years of deliberately shrinking this book, the balance grew again in 2026, and property lending brought in $31M of fees in the second quarter. What caps it is size against the bank's own capital: the property book sits at 124% of equity, against a 160% limit.
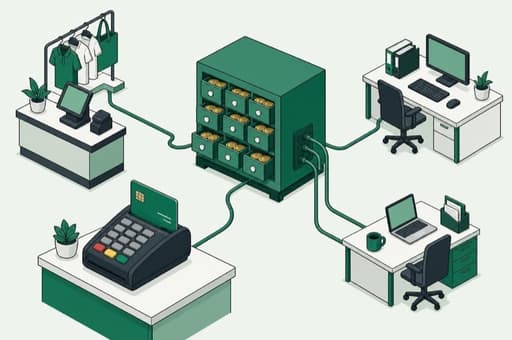
Treasury management and payments
The plumbing companies pay for: collecting receipts, running payroll, taking card payments. Account service charges ran $144M in the second quarter, growing at high single digits — and the deposits it drags in are the cheapest funding the bank has.
Competes with Treasury management (PNC) · Treasury management (Citizens Financial Group) · Treasury management (KeyBank)
In plain English
Every business needs to get paid, pay its people, and see where its cash sits. M&T sells the machinery for that — the accounts, the payment tools, the card readers at the till — and charges monthly fees plus a slice of each card sale.
The fees are welcome; the deposits are the point. Money resting in a company's operating account costs the bank nothing and can be lent out, so winning this work is how M&T defends its cheapest funding. Growth has been running in the high single digits, and it feeds the 2026 fee target of $2.8–2.85B.
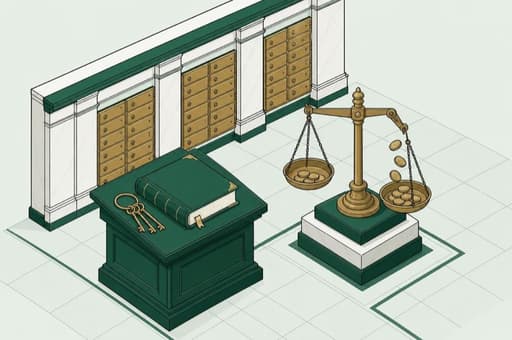
Wilmington Trust
The record-keeping and safekeeping arm for big financial structures, plus money management for wealthy families: $1.56B of revenue in 2025, more of it fees than interest, and roughly $80B of client money managed. Flat for years.
Competes with Corporate trust (BNY) · Corporate Trust (Computershare) · Wealth and fiduciary services (Northern Trust)
In plain English
When a pile of loans is bundled up and sold to investors, somebody neutral has to hold the paperwork, count the money coming in and pay each investor their share. Wilmington Trust does that job, for clients in more than 90 countries, and separately manages money for wealthy families and their estates.
It is the fee-heaviest part of M&T: $907M of the segment's $1.56B came from fees rather than interest last year. Revenue has drifted down since 2023, partly because a fund-management business was sold off that year — though the corporate work was strong in the United States and Europe this year.


 Retail BankRoughly 900 branches from Maine to Virginia, plus everyday accounts, small-business banking and consumer loans. Half of all revenue — $4.87B in 2025 — but it earned less than the year before as rate cuts shrank the value of its cheap deposits.
Roughly 900 branches from Maine to Virginia, plus everyday accounts, small-business banking and consumer loans. Half of all revenue — $4.87B in 2025 — but it earned less than the year before as rate cuts shrank the value of its cheap deposits.
In plain English
This is the part with a front door. People and small businesses keep their spending money in accounts at an M&T branch, and the bank pays them little or nothing for it — $43.9B sits in accounts paying no interest at all. That money is lent back out at much higher rates, and the gap between the two is the profit.
When interest rates fall, the money a bank makes simply from holding cheap deposits shrinks. That is why this half earned less last year than the year before — revenue $4.87B against $5.10B — while the commercial side grew.
Competes with Chase consumer branches (JPMorgan) · Citizens consumer bank (Citizens Financial Group) · TD Bank US retail branches (TD Bank)
 Auto, recreational and home-equity lendingCar, camper, boat and home-equity loans — the vehicle paper largely written at dealerships and handed to M&T. $12.15B of car loans, $7.93B of home equity, $3.72B of recreational vehicles and boats, and the book is growing.
Car, camper, boat and home-equity loans — the vehicle paper largely written at dealerships and handed to M&T. $12.15B of car loans, $7.93B of home equity, $3.72B of recreational vehicles and boats, and the book is growing.
In plain English
Buy a car, an RV or a boat and the dealer usually arranges the loan right there at the desk. M&T is one of the banks behind that desk: it takes the loan onto its books, and the customer pays it back with interest for years. Home-equity lines work the other way round — a homeowner borrows against the value of the house.
It is a volume business, so the money is made on the interest and lost on repossession: when used cars and used boats fetch less, the loss on a loan that goes bad is bigger. Bank-wide, losses ran at about 23 cents per hundred dollars of loans last quarter.
Competes with LightStream recreational and marine loans (Truist) · Auto finance (Ally Financial)
 Residential mortgage sub-servicingM&T collects and administers other companies' home loans for a fee, owning none of them. Lakeview moved a batch across in June 2026, guided to $30–40M a year at about half margin from the third quarter.
M&T collects and administers other companies' home loans for a fee, owning none of them. Lakeview moved a batch across in June 2026, guided to $30–40M a year at about half margin from the third quarter.
In plain English
Somebody has to take the monthly mortgage payment, chase it when it is late, hold the tax and insurance money and send the statements. Lenders hire that job out. M&T does it for Lakeview Loan Servicing, a mortgage company, and for firms related to it — they pay a fee per loan, and M&T carries none of the mortgages itself.
As management put it, "they just pay us a fee to service those loans… there's nothing to hedge." Dull, steady work: the newest batch, moved across from the rival servicer Mr. Cooper in June 2026, was guided to $30–40M a year at roughly half margin.
Competes with Mr. Cooper sub-servicing platform (Rocket) · Sub-servicing (Cenlar)
 Commercial BankLoans and banking for mid-sized and large companies in M&T's own states: $2.95B of revenue in 2025 and $66.0B of business loans by mid-2026. This is the side that is growing — fees rose 18% in a year.
Loans and banking for mid-sized and large companies in M&T's own states: $2.95B of revenue in 2025 and $66.0B of business loans by mid-2026. This is the side that is growing — fees rose 18% in a year.
In plain English
Think of the companies on a regional main street that are too big for a small-business loan and too small for Wall Street — a manufacturer, a hospital group, a property developer. This is the bank they call. M&T lends them money, holds their working cash, and charges for arranging the larger deals.
It is now the growing side of the house. Business loans reached $66.0B by mid-2026, with new money going to mid-sized companies, to lenders who need short-term funding, and to large institutional property borrowers. Fees grew 18% over the year, and money set aside for loans that might sour fell to $23M in the quarter from $60M.
Competes with KeyBank commercial banking (KeyBank) · Fifth Third commercial banking (Fifth Third) · Huntington commercial banking (Huntington)
 Commercial real estate platformLending against apartment blocks and offices — $24.5B on the books, $7.12B of it apartments — plus M&T Realty Capital, which writes loans and passes them to Fannie Mae and Freddie Mac. It grew in 2026 for the first time since 2021.
Lending against apartment blocks and offices — $24.5B on the books, $7.12B of it apartments — plus M&T Realty Capital, which writes loans and passes them to Fannie Mae and Freddie Mac. It grew in 2026 for the first time since 2021.
In plain English
Two ways to lend on a building. M&T can keep the loan and collect the interest, or, through M&T Realty Capital, write it and pass it to the government-backed housing lenders Fannie Mae and Freddie Mac, taking a fee and keeping the job of collecting the payments — it looks after more than 1,500 such loans, over $28B worth.
In 2025 it wrote as much for sale as it kept. After years of deliberately shrinking this book, the balance grew again in 2026, and property lending brought in $31M of fees in the second quarter. What caps it is size against the bank's own capital: the property book sits at 124% of equity, against a 160% limit.
Competes with Fannie Mae agency multifamily lending (Walker & Dunlop) · Freddie Mac multifamily lending (Berkadia)
 Treasury management and paymentsThe plumbing companies pay for: collecting receipts, running payroll, taking card payments. Account service charges ran $144M in the second quarter, growing at high single digits — and the deposits it drags in are the cheapest funding the bank has.
The plumbing companies pay for: collecting receipts, running payroll, taking card payments. Account service charges ran $144M in the second quarter, growing at high single digits — and the deposits it drags in are the cheapest funding the bank has.
In plain English
Every business needs to get paid, pay its people, and see where its cash sits. M&T sells the machinery for that — the accounts, the payment tools, the card readers at the till — and charges monthly fees plus a slice of each card sale.
The fees are welcome; the deposits are the point. Money resting in a company's operating account costs the bank nothing and can be lent out, so winning this work is how M&T defends its cheapest funding. Growth has been running in the high single digits, and it feeds the 2026 fee target of $2.8–2.85B.
Competes with Treasury management (PNC) · Treasury management (Citizens Financial Group) · Treasury management (KeyBank)
 Wilmington TrustThe record-keeping and safekeeping arm for big financial structures, plus money management for wealthy families: $1.56B of revenue in 2025, more of it fees than interest, and roughly $80B of client money managed. Flat for years.
The record-keeping and safekeeping arm for big financial structures, plus money management for wealthy families: $1.56B of revenue in 2025, more of it fees than interest, and roughly $80B of client money managed. Flat for years.
In plain English
When a pile of loans is bundled up and sold to investors, somebody neutral has to hold the paperwork, count the money coming in and pay each investor their share. Wilmington Trust does that job, for clients in more than 90 countries, and separately manages money for wealthy families and their estates.
It is the fee-heaviest part of M&T: $907M of the segment's $1.56B came from fees rather than interest last year. Revenue has drifted down since 2023, partly because a fund-management business was sold off that year — though the corporate work was strong in the United States and Europe this year.
Competes with Corporate trust (BNY) · Corporate Trust (Computershare) · Wealth and fiduciary services (Northern Trust)
Named in filings, launches and programs
- Securities portfolio and funding deskSegmentThe bank's own $38.7B of bonds yielding 4.29% — parked money that keeps it liquid; it swung from a drag in 2024 to $313M in 2025.
- Bayview Lending GroupBrandA 20% stake in a private commercial mortgage company; it paid M&T $47M in the second quarter of 2026 — lumpy, but management calls it recurring.
- Business Banking and SBA 7(a) lendingServiceGovernment-guaranteed small-business loans: 2,701 of them for $294M in 2025, the most by count of any lender in M&T's own states.
- Residential mortgage lendingProduct lineHome loans written through the branches — $127M of mortgage revenue in the second quarter of 2026; servicing rights now carried at market value, adding $197M of capital.
- Capital markets and investment bankingService · RampingArranging loan syndicates and interest-rate swaps for borrowers — $22M of trading revenue in the second quarter of 2026; to be reported as its own line.
- CRE WarehouseProduct line · AnnouncedShort-term lending to other property lenders, which management described in July 2026 as a business it is just starting up.
- Fund banking, mortgage warehouse and institutional CREProduct lineLoans to funds and to other lenders rather than to operating companies — warehouse and institutional property books each grew more than $300M in the second quarter of 2026.
- Affordability businessesProduct lineLending on affordable housing, one of the five businesses run under the commercial property group.
- M&T Capital and Leasing / M&T Equipment FinanceBrandEquipment finance and leasing for business customers — roughly $600M of business leases on the books.
- LEAF, lender finance and healthcare specialty lendingProduct lineNiche lending desks — equipment, loans to other lenders, and healthcare — all named as contributors to the loan growth of mid-2026.
- Wilmington Trust CLO trustee and loan administrationServiceThe neutral record-keeper for bundled corporate loans and the holding shells built around them — steady fee work inside the trust arm.
- Wilmington Funds ManagementBrandThe registered managers behind roughly $80B of client money in the wealth and investment business.
- Brokerage servicesServiceInvestment accounts sold to customers: brokerage and trading together brought $59M in the second quarter of 2026, most of it ordinary brokerage fees.
- RDC.AI commercial credit monitoringPlatformA bought-in platform that watches business borrowers for early signs of trouble, used by more than 1,200 of M&T's relationship managers and credit staff.
Securities portfolio and funding deskSegment
The bank's own $38.7B of bonds yielding 4.29% — parked money that keeps it liquid; it swung from a drag in 2024 to $313M in 2025.
Bayview Lending GroupBrand
A 20% stake in a private commercial mortgage company; it paid M&T $47M in the second quarter of 2026 — lumpy, but management calls it recurring.
Business Banking and SBA 7(a) lendingService
Government-guaranteed small-business loans: 2,701 of them for $294M in 2025, the most by count of any lender in M&T's own states.
Residential mortgage lendingProduct line
Home loans written through the branches — $127M of mortgage revenue in the second quarter of 2026; servicing rights now carried at market value, adding $197M of capital.
Capital markets and investment bankingService · Ramping
Arranging loan syndicates and interest-rate swaps for borrowers — $22M of trading revenue in the second quarter of 2026; to be reported as its own line.
CRE WarehouseProduct line · Announced
Short-term lending to other property lenders, which management described in July 2026 as a business it is just starting up.
Fund banking, mortgage warehouse and institutional CREProduct line
Loans to funds and to other lenders rather than to operating companies — warehouse and institutional property books each grew more than $300M in the second quarter of 2026.
Affordability businessesProduct line
Lending on affordable housing, one of the five businesses run under the commercial property group.
M&T Capital and Leasing / M&T Equipment FinanceBrand
Equipment finance and leasing for business customers — roughly $600M of business leases on the books.
LEAF, lender finance and healthcare specialty lendingProduct line
Niche lending desks — equipment, loans to other lenders, and healthcare — all named as contributors to the loan growth of mid-2026.
Wilmington Trust CLO trustee and loan administrationService
The neutral record-keeper for bundled corporate loans and the holding shells built around them — steady fee work inside the trust arm.
Wilmington Funds ManagementBrand
The registered managers behind roughly $80B of client money in the wealth and investment business.
Brokerage servicesService
Investment accounts sold to customers: brokerage and trading together brought $59M in the second quarter of 2026, most of it ordinary brokerage fees.
RDC.AI commercial credit monitoringPlatform
A bought-in platform that watches business borrowers for early signs of trouble, used by more than 1,200 of M&T's relationship managers and credit staff.