
Synchrony Financial (SYF)
Issues partner-based cards and point-of-sale financing across retail, digital, healthcare, and lifestyle markets.
Something off on this page? Send us feedback.
Synchrony's name is rarely the one on the card. It is the bank behind other companies' store cards — Amazon, Lowe's, PayPal, Sam's Club and TJX, five partners that bring in more than half its card income, plus the card a dentist offers. It lends the money, carries the risk, and hands much of the profit back to the brand on the front. Savers' deposits pay for most of the lending.
Item facts: FY2025 · year ended Dec 31, 2025, from filings, earnings calls and company pages.
Judgment weights, not filed revenue
The band summarizes business focus and direction. ~ marks estimates.
7 in detail · 15 more below
Digital platform
The cards that live inside apps and web checkouts: Amazon, PayPal, Venmo, eBay. Biggest of the five books at $6.4B a year in interest and fees, with spending on it speeding up four quarters running. PayPal and Venmo together clear a tenth of that line company-wide.
Competes with Prime Visa co-brand card (Chase) · Pay in 4 installments (Klarna) · Retail Services card programs (Citi)
In plain English
Buy a television on the Amazon store card, or tap PayPal Credit at an online checkout, and the money behind the screen is Synchrony's. The shop keeps the customer and the brand; Synchrony keeps the loan.
It earns the way any card lender does: interest on balances people carry from one month to the next, plus fees when a payment is late or a special financing deal runs its course. Part of that profit then goes straight back to Amazon or PayPal, because the partner is the reason the customer was there at all.
Home & Auto platform
Lowe's, furniture, flooring, powersports and car repair. The largest pile of loans in the company — about $30B in the middle of 2026 — but only the second-largest earner, because so much of it is lent on low-rate promotions. It fell for a year, then turned up.
Competes with Home-improvement card programs (Wells Fargo) · Retail Services home-improvement cards (Citi) · Furniture & specialty card programs (Bread Financial)
In plain English
Nobody pays cash for a new kitchen floor. Or a mattress, a riding mower, a transmission rebuild — this is the book of big, occasional purchases, with Lowe's at the centre of it for more than forty-five years.
People take the card to spread the cost, often on a special financing offer that keeps the interest low or nil for a stretch. That makes this the largest pile of loans in the company but not the largest earner: the money comes from people who still owe when the offer ends, from late payments, and from sheer volume. When houses stop changing hands, this business goes quiet.
Diversified & Value platform
Sam's Club, TJX and, since September 2025, Walmart. Fastest-growing of the five books — spending on it went from up three percent to up twelve in a year — and the one that holds up best when shoppers turn careful.
Competes with Costco Anywhere Visa (Citi) · Mass-merchant co-brand cards (Capital One) · Value & off-price card programs (Bread Financial)
In plain English
Warehouse clubs and off-price chains — the places people shop to make the money go further.
Synchrony issues the cards for Sam's Club and TJX, and now, through the payments app OnePay, a new Walmart card. Little of this book is sold on special financing deals, so more customers carry an ordinary balance and each dollar lent earns more here than it does in home improvement. The growth is not Americans buying more stuff; it is programs moving across from the banks that used to run them.
OnePay Walmart card program
The new Walmart card, run inside OnePay's app rather than anything carrying Synchrony's name. One year of sign-ups so far, over half of them Walmart+ members. Balances are not disclosed; watch whether losses stay inside the 5.5–6% the company targets.
Competes with Former Walmart card (Capital One) · Target Circle Card (TD Bank) · Checkout installments at Walmart (Affirm)
In plain English
Walmart's card program changed hands, and Synchrony won it. The card itself lives inside OnePay — a payments app, not a Synchrony screen — while Synchrony puts up the money, decides who qualifies and collects the repayments.
Walmart+ members get five percent back, and more than half the new accounts are theirs. It is a slow earner on purpose: fresh cardholders borrow modestly at first and some stop paying later, so the program weighs on returns while it fills up. How big it finally gets depends on how many of Walmart's shoppers take one.
CareCredit
The card offered at the dentist, the vet and the hearing clinic when insurance stops paying. Roughly 290,000 practices accept it, including most US veterinary offices. Pet and hearing care have grown every quarter; cosmetic work stays soft.
Competes with Health Advantage card (Wells Fargo) · Alphaeon Credit line (Alphaeon) · Point-of-care installment loans (Cherry)
In plain English
The bill lands after the insurance stops: dental implants, a dog's operation, new hearing aids. Few households have that sitting in the bank.
So the practice offers a card at the front desk — the provider chooses the financing here, not the patient — and the patient pays it down over months while Synchrony earns interest on what is still owed. Synchrony keeps practices close by plugging into the scheduling and billing software dental and vet offices already run on all day, and pet insurers send their reimbursements straight back onto the same account.
Synchrony Bank deposits
The branchless savings bank that pays for the lending — deposits gathered online, grown to $82.8B by mid-2026. It let expensive balances leave in 2025 rather than chase savers, and cheaper funding was the biggest lift to the lending margin in spring 2026.
Competes with Marcus high-yield savings (Goldman Sachs) · Online savings and CDs (Ally Bank)
In plain English
No branches, no tellers, no queue. Just a website where anyone can leave cash in a savings account or lock it away in a certificate of deposit for a fixed term.
That money is the raw material for everything else. Synchrony borrows from savers at savings rates and lends to cardholders at card rates, and the gap between the two is the whole business. So this side has one job: keep the funding cheap and keep it from walking out. When the rate it pays savers dropped in spring 2026, that was the single biggest lift to the gap that quarter.
Lifestyle platform
The smallest book at $1.1B a year: outdoor gear, powersports, music, sewing, jewellery and specialty clothing, with DICK'S and Suzuki among the names. It earns the least per dollar lent of the five and swings with how confident shoppers feel.
Competes with Specialty-apparel & jewellery card programs (Bread Financial) · Retail Services specialty programs (Citi)
In plain English
This is the corner where people buy what they fancy rather than what they need: outdoor kit, quad bikes, guitars, sewing machines, jewellery, clothes.
Much of it runs on cards Synchrony owns rather than a shop's — Sport, Music & Sound, Sewing & More, Luxury — each usable across a whole set of stores in one category, alongside partners like DICK'S and Suzuki's dealer network. A lot is lent as fixed monthly payments arranged in showrooms, which earns less per dollar than a card people carry a balance on. It shrank through 2025 and has grown for three quarters since.


 Digital platformThe cards that live inside apps and web checkouts: Amazon, PayPal, Venmo, eBay. Biggest of the five books at $6.4B a year in interest and fees, with spending on it speeding up four quarters running. PayPal and Venmo together clear a tenth of that line company-wide.
The cards that live inside apps and web checkouts: Amazon, PayPal, Venmo, eBay. Biggest of the five books at $6.4B a year in interest and fees, with spending on it speeding up four quarters running. PayPal and Venmo together clear a tenth of that line company-wide.
In plain English
Buy a television on the Amazon store card, or tap PayPal Credit at an online checkout, and the money behind the screen is Synchrony's. The shop keeps the customer and the brand; Synchrony keeps the loan.
It earns the way any card lender does: interest on balances people carry from one month to the next, plus fees when a payment is late or a special financing deal runs its course. Part of that profit then goes straight back to Amazon or PayPal, because the partner is the reason the customer was there at all.
Competes with Prime Visa co-brand card (Chase) · Pay in 4 installments (Klarna) · Retail Services card programs (Citi)
 Home & Auto platformLowe's, furniture, flooring, powersports and car repair. The largest pile of loans in the company — about $30B in the middle of 2026 — but only the second-largest earner, because so much of it is lent on low-rate promotions. It fell for a year, then turned up.
Lowe's, furniture, flooring, powersports and car repair. The largest pile of loans in the company — about $30B in the middle of 2026 — but only the second-largest earner, because so much of it is lent on low-rate promotions. It fell for a year, then turned up.
In plain English
Nobody pays cash for a new kitchen floor. Or a mattress, a riding mower, a transmission rebuild — this is the book of big, occasional purchases, with Lowe's at the centre of it for more than forty-five years.
People take the card to spread the cost, often on a special financing offer that keeps the interest low or nil for a stretch. That makes this the largest pile of loans in the company but not the largest earner: the money comes from people who still owe when the offer ends, from late payments, and from sheer volume. When houses stop changing hands, this business goes quiet.
Competes with Home-improvement card programs (Wells Fargo) · Retail Services home-improvement cards (Citi) · Furniture & specialty card programs (Bread Financial)
 Diversified & Value platformSam's Club, TJX and, since September 2025, Walmart. Fastest-growing of the five books — spending on it went from up three percent to up twelve in a year — and the one that holds up best when shoppers turn careful.
Sam's Club, TJX and, since September 2025, Walmart. Fastest-growing of the five books — spending on it went from up three percent to up twelve in a year — and the one that holds up best when shoppers turn careful.
In plain English
Warehouse clubs and off-price chains — the places people shop to make the money go further.
Synchrony issues the cards for Sam's Club and TJX, and now, through the payments app OnePay, a new Walmart card. Little of this book is sold on special financing deals, so more customers carry an ordinary balance and each dollar lent earns more here than it does in home improvement. The growth is not Americans buying more stuff; it is programs moving across from the banks that used to run them.
Competes with Costco Anywhere Visa (Citi) · Mass-merchant co-brand cards (Capital One) · Value & off-price card programs (Bread Financial)
 OnePay Walmart card programThe new Walmart card, run inside OnePay's app rather than anything carrying Synchrony's name. One year of sign-ups so far, over half of them Walmart+ members. Balances are not disclosed; watch whether losses stay inside the 5.5–6% the company targets.
The new Walmart card, run inside OnePay's app rather than anything carrying Synchrony's name. One year of sign-ups so far, over half of them Walmart+ members. Balances are not disclosed; watch whether losses stay inside the 5.5–6% the company targets.
In plain English
Walmart's card program changed hands, and Synchrony won it. The card itself lives inside OnePay — a payments app, not a Synchrony screen — while Synchrony puts up the money, decides who qualifies and collects the repayments.
Walmart+ members get five percent back, and more than half the new accounts are theirs. It is a slow earner on purpose: fresh cardholders borrow modestly at first and some stop paying later, so the program weighs on returns while it fills up. How big it finally gets depends on how many of Walmart's shoppers take one.
Competes with Former Walmart card (Capital One) · Target Circle Card (TD Bank) · Checkout installments at Walmart (Affirm)
 CareCreditThe card offered at the dentist, the vet and the hearing clinic when insurance stops paying. Roughly 290,000 practices accept it, including most US veterinary offices. Pet and hearing care have grown every quarter; cosmetic work stays soft.
The card offered at the dentist, the vet and the hearing clinic when insurance stops paying. Roughly 290,000 practices accept it, including most US veterinary offices. Pet and hearing care have grown every quarter; cosmetic work stays soft.
In plain English
The bill lands after the insurance stops: dental implants, a dog's operation, new hearing aids. Few households have that sitting in the bank.
So the practice offers a card at the front desk — the provider chooses the financing here, not the patient — and the patient pays it down over months while Synchrony earns interest on what is still owed. Synchrony keeps practices close by plugging into the scheduling and billing software dental and vet offices already run on all day, and pet insurers send their reimbursements straight back onto the same account.
Competes with Health Advantage card (Wells Fargo) · Alphaeon Credit line (Alphaeon) · Point-of-care installment loans (Cherry)
 Synchrony Bank depositsThe branchless savings bank that pays for the lending — deposits gathered online, grown to $82.8B by mid-2026. It let expensive balances leave in 2025 rather than chase savers, and cheaper funding was the biggest lift to the lending margin in spring 2026.
The branchless savings bank that pays for the lending — deposits gathered online, grown to $82.8B by mid-2026. It let expensive balances leave in 2025 rather than chase savers, and cheaper funding was the biggest lift to the lending margin in spring 2026.
In plain English
No branches, no tellers, no queue. Just a website where anyone can leave cash in a savings account or lock it away in a certificate of deposit for a fixed term.
That money is the raw material for everything else. Synchrony borrows from savers at savings rates and lends to cardholders at card rates, and the gap between the two is the whole business. So this side has one job: keep the funding cheap and keep it from walking out. When the rate it pays savers dropped in spring 2026, that was the single biggest lift to the gap that quarter.
Competes with Marcus high-yield savings (Goldman Sachs) · Online savings and CDs (Ally Bank)
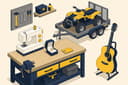 Lifestyle platformThe smallest book at $1.1B a year: outdoor gear, powersports, music, sewing, jewellery and specialty clothing, with DICK'S and Suzuki among the names. It earns the least per dollar lent of the five and swings with how confident shoppers feel.
The smallest book at $1.1B a year: outdoor gear, powersports, music, sewing, jewellery and specialty clothing, with DICK'S and Suzuki among the names. It earns the least per dollar lent of the five and swings with how confident shoppers feel.
In plain English
This is the corner where people buy what they fancy rather than what they need: outdoor kit, quad bikes, guitars, sewing machines, jewellery, clothes.
Much of it runs on cards Synchrony owns rather than a shop's — Sport, Music & Sound, Sewing & More, Luxury — each usable across a whole set of stores in one category, alongside partners like DICK'S and Suzuki's dealer network. A lot is lent as fixed monthly payments arranged in showrooms, which earns less per dollar than a card people carry a balance on. It shrank through 2025 and has grown for three quarters since.
Competes with Specialty-apparel & jewellery card programs (Bread Financial) · Retail Services specialty programs (Citi)
Named in filings, launches and programs
- Synchrony Pay LaterProduct line · RampingInstallment loans sold beside the cards at 6,200-plus merchant locations; most run six to twelve months, and management says pairing the two lifts partner sales.
- Amazon Store Card and Amazon Secured CardCustomer programCards that work at Amazon and nowhere else — a fifteen-year-plus relationship renewed in 2025, with Chase's Prime Visa sitting beside them at the same checkout.
- PayPal and Venmo card programsCustomer programCredit inside PayPal and Venmo; together above a tenth of the year's interest and fees, which makes PayPal one of only three partners big enough to be named.
- Sam's Club programCustomer programThe warehouse club's card — on its own, more than a tenth of the year's interest and fees on loans.
- TJX Companies programCustomer programThe off-price chains' card, one of the five partner programs that together make a little over half of interest and fees.
- MyLowe's Pro Rewards cardCustomer programLowe's card for tradespeople, bought from American Express and taken over in April 2026, with $45M set aside up front for loans that may go bad.
- Synchrony-branded network cardsBrandSynchrony HOME, Car Care, Project, Luxury, Sport, Music & Sound, Sewing & More — cards Synchrony owns that work across many shops in one category.
- Synchrony general-purpose MastercardProductA Synchrony card usable anywhere Mastercard is taken; holders can split an Apple Pay Online purchase into fixed monthly payments.
- CareCredit Dual CardProductA CareCredit account that also works outside the provider network — everyday spending on a card built for health bills.
- Versatile CreditBrandA 2025 acquisition: one application desk that connects a shop to thirty-plus lenders at once, with Synchrony earning a referral fee.
- Synchrony PRISMPlatformThe in-house system that decides who is approved and on what terms — management cites it as part of why partners pick Synchrony.
- Synchrony Marketplace / Joy HuntPlatformA shopping-offers site with AI-powered search, and the place the new ChatGPT plugin sends customers.
- OpenAI collaborationEcosystem · AnnouncedAnnounced August 2026: a ChatGPT plugin pointing at Synchrony's offers site, plus OpenAI models used internally. No terms given, no revenue attached.
- CareCredit–Stripe partnershipCustomer program · AnnouncedAnnounced August 2026 to widen where clinics and practices can offer CareCredit to patients; terms not disclosed.
- 2025–2026 partner addsCustomer program · RampingBob's Discount Furniture, RH, DICK'S, Chico's, Toro, Polaris, American Eagle, Ashley, Suzuki, Roto-Rooter — over seventy-five partners added or renewed in 2025.
Synchrony Pay LaterProduct line · Ramping
Installment loans sold beside the cards at 6,200-plus merchant locations; most run six to twelve months, and management says pairing the two lifts partner sales.
Amazon Store Card and Amazon Secured CardCustomer program
Cards that work at Amazon and nowhere else — a fifteen-year-plus relationship renewed in 2025, with Chase's Prime Visa sitting beside them at the same checkout.
PayPal and Venmo card programsCustomer program
Credit inside PayPal and Venmo; together above a tenth of the year's interest and fees, which makes PayPal one of only three partners big enough to be named.
Sam's Club programCustomer program
The warehouse club's card — on its own, more than a tenth of the year's interest and fees on loans.
TJX Companies programCustomer program
The off-price chains' card, one of the five partner programs that together make a little over half of interest and fees.
MyLowe's Pro Rewards cardCustomer program
Lowe's card for tradespeople, bought from American Express and taken over in April 2026, with $45M set aside up front for loans that may go bad.
Synchrony-branded network cardsBrand
Synchrony HOME, Car Care, Project, Luxury, Sport, Music & Sound, Sewing & More — cards Synchrony owns that work across many shops in one category.
Synchrony general-purpose MastercardProduct
A Synchrony card usable anywhere Mastercard is taken; holders can split an Apple Pay Online purchase into fixed monthly payments.
CareCredit Dual CardProduct
A CareCredit account that also works outside the provider network — everyday spending on a card built for health bills.
Versatile CreditBrand
A 2025 acquisition: one application desk that connects a shop to thirty-plus lenders at once, with Synchrony earning a referral fee.
Synchrony PRISMPlatform
The in-house system that decides who is approved and on what terms — management cites it as part of why partners pick Synchrony.
Synchrony Marketplace / Joy HuntPlatform
A shopping-offers site with AI-powered search, and the place the new ChatGPT plugin sends customers.
OpenAI collaborationEcosystem · Announced
Announced August 2026: a ChatGPT plugin pointing at Synchrony's offers site, plus OpenAI models used internally. No terms given, no revenue attached.
CareCredit–Stripe partnershipCustomer program · Announced
Announced August 2026 to widen where clinics and practices can offer CareCredit to patients; terms not disclosed.
2025–2026 partner addsCustomer program · Ramping
Bob's Discount Furniture, RH, DICK'S, Chico's, Toro, Polaris, American Eagle, Ashley, Suzuki, Roto-Rooter — over seventy-five partners added or renewed in 2025.